Issue · Budget & Taxes

Budget & Taxes (Business Taxes)

Every budget & taxes bill, vote, and legislator stance in Connecticut, automatically classified by Maddy, our AI policy reader.

Total bills
56
2026 Regular Session
Top supporter
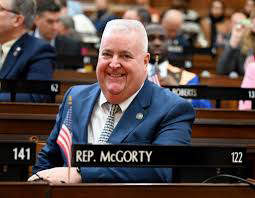
Ben McGorty
100% support rate
Top opponent
Aimee Berger-Girvalo
33% support rate
Ranked legislators
10
5 support · 5 oppose
Key legislators

Who's moving business taxes in Connecticut

Legislators moving business taxes in Connecticut
Legislator Party Stance Support rate Decisive votes
Ben McGorty
Ben McGorty House · District 122
R
Strong +
100% 3
Bill Pizzuto
Bill Pizzuto House · District 71
R
Strong +
100% 3
Billy Buckbee
Billy Buckbee House · District 67
R
Strong +
100% 3
Brian Lanoue
Brian Lanoue House · District 45
R
Strong +
100% 3
Carol Hall
Carol Hall House · District 59
R
Strong +
100% 3
Aimee Berger-Girvalo
Aimee Berger-Girvalo House · District 111
D
Oppose
33% 3
Al Paolillo
Al Paolillo House · District 97
D
Oppose
33% 3
Amy Morrin Bello
Amy Morrin Bello House · District 28
D
Oppose
33% 3
Andre Baker
Andre Baker House · District 124
D
Oppose
33% 3
Anne Hughes
Anne Hughes House · District 135
D
Oppose
33% 3
Showing 51–56 of 56 bills

All budget & taxes bills

in committee · Connecticut · Senate Feb 4, 2026

SB 76: AN ACT ESTABLISHING A CHILD AND DEPENDENT TAX CREDIT AGAINST THE PERSONAL INCOME TAX.

SB 76 creates a $500 tax credit per eligible child or dependent against personal income tax. It directly affects taxpayers with qualifying dependents, including children under 17, disabled dependents or spouses living with them, or seniors 65+ who aren’t a spouse. The credit phases out for single filers and heads of household earning over $200,000, and for married couples filing jointly earning over $400,000, reducing by 10% for each $1,000 of income above those thresholds. This policy provides direct tax relief for families with qualifying dependents while limiting benefits for higher-income households.
in committee · Connecticut · House Feb 4, 2026

HB 5014: AN ACT ESTABLISHING AN INFORMATION TECHNOLOGY APPRENTICESHIP TAX CREDIT.

HB 5014 creates a tax credit for businesses that sponsor apprenticeships in information technology. It allows taxpayers to reduce their state income tax liability by a credit for qualified IT apprenticeship programs. The credit applies to apprenticeships started under approved training programs, directly benefiting employers who hire and train IT apprentices. This policy change provides a financial incentive for companies to develop workforce pipelines in technology fields without altering existing tax rates.
in committee · Connecticut · House Feb 6, 2026

HB 5070: AN ACT REESTABLISHING THE JOB EXPANSION TAX CREDIT PROGRAM.

HB 5070 reestablishes the Job Expansion Tax Credit Program by amending section 12-217pp of the general statutes. The program provides tax credits to businesses that expand their workforce, reducing their state tax liability for qualifying job growth. This bill directly affects eligible businesses by restoring a tax credit opportunity previously established under the program. The legislation focuses on concrete policy restoration without specifying eligibility details or credit amounts.
in committee · Connecticut · House Feb 13, 2026

HB 5204: AN ACT DEDICATING A PORTION OF THE ROOM OCCUPANCY TAX ON SHORT-TERM RENTAL PROPERTIES TO MUNICIPALITIES.

HB 5204 redirects a portion of the state's room occupancy tax collected from short-term rental properties (like Airbnb or vacation rentals) to the local municipalities where those properties are located. This means cities and towns where short-term rentals operate will receive a share of the tax revenue instead of the funds staying solely with the state. The bill amends existing law to require the state to allocate this specific tax portion directly to the municipalities based on where the rentals are situated, providing them with additional local funding.
Sub-Topics Business Taxes Revenue
in committee · Connecticut · Senate Apr 20, 2026

SB 2: AN ACT SUPPORTING LOCAL COMMERCE.

SB 2 exempts small businesses (with less than $10 million in annual revenue) from sales and use taxes on electricity and natural gas purchases. It redirects revenue from an additional 1% sales tax on meals: 50% to the state Tourism Fund and 50% to the municipalities where the meals were purchased. The bill aims to lower operating costs for small commercial and industrial businesses, which could reduce prices passed on to consumers. These changes directly affect small businesses and local governments through tax adjustments and new revenue allocation.
in committee · Connecticut · Senate Feb 4, 2026

SB 66: AN ACT ESTABLISHING A TEMPORARY PERSONAL INCOME TAX DEDUCTION FOR TIPS OR GRATUITIES.

SB 66 would create a temporary tax deduction for workers who declare tips or gratuities on their income tax returns. It allows a deduction of up to $25,000 per year for tips earned during 2026-2028, reducing taxable income for affected workers. The deduction phases out for single filers with incomes over $150,000 and married couples filing jointly over $300,000. This policy directly impacts service industry workers who report tip income, lowering their tax burden for the specified period.
Showing 51 to 56 of 56 bills
Previous 1 … 4 5 6