Issue · Budget & Taxes

Budget & Taxes (Sales Tax)

Every budget & taxes bill, vote, and legislator stance in Connecticut, automatically classified by Maddy, our AI policy reader.

Total bills
66
2026 Regular Session
Top supporter
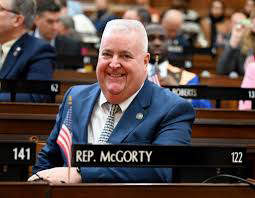
Ben McGorty
100% support rate
Top opponent
Aimee Berger-Girvalo
33% support rate
Ranked legislators
10
5 support · 5 oppose
Key legislators

Who's moving sales tax in Connecticut

Legislators moving sales tax in Connecticut
Legislator Party Stance Support rate Votes
Ben McGorty
Ben McGorty House · District 122
R
Strong +
100% 3
Bill Pizzuto
Bill Pizzuto House · District 71
R
Strong +
100% 3
Billy Buckbee
Billy Buckbee House · District 67
R
Strong +
100% 3
Brian Lanoue
Brian Lanoue House · District 45
R
Strong +
100% 3
Carol Hall
Carol Hall House · District 59
R
Strong +
100% 3
Aimee Berger-Girvalo
Aimee Berger-Girvalo House · District 111
D
Oppose
33% 3
Al Paolillo
Al Paolillo House · District 97
D
Oppose
33% 3
Amy Morrin Bello
Amy Morrin Bello House · District 28
D
Oppose
33% 3
Andre Baker
Andre Baker House · District 124
D
Oppose
33% 3
Anne Hughes
Anne Hughes House · District 135
D
Oppose
33% 3
Showing 31–40 of 66 bills

All budget & taxes bills

in committee · Connecticut · Senate Feb 10, 2026

SB 106: AN ACT EXEMPTING DOG GROOMING SERVICES FROM THE SALES AND USE TAXES.

SB 106 would remove the sales and use tax from dog grooming services in the state. This change directly affects dog groomers (who would pay less tax on their services) and pet owners (who would pay less for grooming). The bill achieves this by amending the state tax code to specifically exempt dog grooming services from the standard sales tax.
in committee · Connecticut · House Feb 10, 2026

HB 5129: AN ACT ESTABLISHING A SURCHARGE ON HIGH-VALUE RECREATIONAL VESSELS AND CONCERNING THE USE OF THE REVENUE GENERATED.

HB 5129 would require owners of high-value recreational vessels (such as expensive boats and yachts) to pay an additional surcharge. The revenue generated from this surcharge would be dedicated to reducing and eliminating the property tax on motor vehicles, including cars and trucks. This bill directly affects vessel owners through a new fee and vehicle owners through potential tax relief, creating a funding mechanism to lower vehicle taxes by taxing a specific category of recreational boats.
in committee · Connecticut · Senate Feb 4, 2026

SB 73: AN ACT ESTABLISHING A NONREFUNDABLE PERSONAL INCOME TAX CREDIT FOR THE PURCHASE OF A GUN SAFE.

This bill establishes a nonrefundable personal income tax credit of up to $150 for individuals who purchase a gun safe for personal use. The credit reduces the amount of state income tax owed but cannot result in a refund if the credit exceeds the tax liability. It directly affects individual taxpayers who buy gun safes, providing a tax benefit for this specific purchase. The policy change creates a new tax incentive without altering firearm regulations or safety standards.
in committee · Connecticut · Senate Feb 4, 2026

SB 74: AN ACT ESTABLISHING A TAX CREDIT FOR DAIRY FARMERS.

SB 74 would create a $20 million state tax credit for dairy farmers to help offset income losses during periods when milk prices drop. The credit directly affects dairy farmers in the state who experience cyclical price fluctuations in milk sales. The bill establishes this tax credit as a fixed pool, meaning it would provide financial relief to eligible farmers when milk prices fall below certain levels. This is a direct policy change to support dairy farm revenue stability, not a procedural measure.
Sub-Topics Business Taxes Sales Tax Tax Credits Tags Agriculture
in committee · Connecticut · Senate Feb 4, 2026

SB 60: AN ACT CONCERNING THE SALES AND USE TAXES RATE.

This bill would lower Connecticut's general sales tax rate from 7% to 6% and eliminate a separate 1% tax on meals sold at restaurants, caterers, and grocery stores. It directly affects businesses selling taxable goods and meals, as well as consumers who pay these taxes. The key changes are reducing the overall sales tax rate and removing the additional tax specifically for food purchases. The bill aims to decrease the tax burden for these transactions.
in committee · Connecticut · House Feb 10, 2026

HB 5136: AN ACT DEDICATING THE REVENUE GENERATED FROM SALES AND USE TAXES IMPOSED ON MEALS SOLD BY AN EATING ESTABLISHMENT, CATERER OR GROCERY STORE TO CERTAIN PURPOSES.

HB 5136 dedicates an additional 1% sales and use tax collected on meals sold by restaurants, caterers, and grocery stores to two specific purposes. The revenue must be distributed to the municipalities where the tax was collected and deposited into the state's Tourism Fund (under § 10-395b). This bill directly affects businesses selling prepared meals and the local governments receiving the redistributed funds. It creates a new, mandatory allocation for this tax revenue stream without changing the tax rate itself.
Sub-Topics Revenue Sales Tax
in committee · Connecticut · House Feb 10, 2026

HB 5105: AN ACT EXEMPTING HANDICAP RAMPS FOR RESIDENTIAL USE FROM THE SALES AND USE TAXES.

HB 5105 would exempt handicap ramps purchased for residential use from the state's sales and use taxes. This directly affects homeowners with disabilities who need these ramps installed at their primary residence. The bill amends tax law to remove the sales tax requirement specifically for residential handicap ramps, making them more affordable. It does not change tax rules for commercial or non-residential ramp installations. The policy change is limited to removing an existing tax burden on these essential accessibility devices.
in committee · Connecticut · Senate Feb 11, 2026

SB 187: AN ACT CONCERNING THE DISTRIBUTION OF THE SALES AND USE TAXES IMPOSED ON MEALS SOLD BY AN EATING ESTABLISHMENT, CATERER OR GROCERY STORE.

SB 187 redirects the additional 1% sales tax collected on meals sold by restaurants, caterers, and grocery stores to the specific local municipalities where the tax was paid. This changes the current system by ensuring the tax revenue stays in the community where the sale occurred, rather than going to the state. The bill directly affects local governments, providing them with new funding from this tax stream without altering the tax rate or burden on businesses or consumers.
Sub-Topics Revenue Sales Tax
in committee · Connecticut · Senate Feb 4, 2026

SB 49: AN ACT ELIMINATING THE HIGHWAY USE TAX.

SB 49 eliminates the highway use tax by amending Section 12-493a of the general statutes to remove this tax provision from state law. It directly affects vehicle owners who previously paid this tax as part of registration or road usage fees. The bill’s key mechanism is the deletion of the tax requirement from existing statutes, removing the obligation for taxpayers. This policy change would end the collection of the highway use tax without creating new fees or exemptions. The bill’s purpose statement explicitly states it aims to eliminate the highway use tax entirely.
Sub-Topics Sales Tax
in committee · Connecticut · House Feb 4, 2026

HB 5011: AN ACT ELIMINATING THE HIGHWAY USE TAX.

HB 5011 eliminates the highway use tax by amending Section 12-493a of the general statutes. This bill directly affects drivers who previously paid this tax on vehicle registration or use. The key change removes the tax requirement from state law, resulting in no additional cost for affected drivers under this provision. The bill focuses solely on repealing the tax without altering other vehicle-related fees or requirements.
Sub-Topics Sales Tax
Showing 31 to 40 of 66 bills
Previous 1 3 4 5 7 Next