

Education expenses: School Choice Flex Account Act of 2025.
Summary
(1) Existing law establishes a system of elementary and secondary education in this state. This system consists of the public and private schools that provide instruction in kindergarten and in grades 1 to 12, inclusive. This bill would enact the School Choice Flex Account Act of 2025 and establish the School Choice Flex Account (SCFA) Trust, to be known as the SCFA Trust, as a fund within the State Treasury to be administered by the SCFA Trust Board. For the 2027–28 to 2030–31, inclusive, school years, the bill would authorize certain children eligible to be enrolled in kindergarten or any of grades 1 to 12, inclusive, to establish an SCFA or Special Education Flex Account (SEFA) , based on parent or guardian income. The bill would, beginning with the 2031–32 school year, authorize every child eligible to be enrolled in kindergarten or any of grades 1 to 12, inclusive, to establish an SCFA or SEFA. The bill would credit a deposit amount to the account of every eligible student enrolled in an eligible school for tuition and certain school expenses. The bill would specify the deposit amounts for the 2027–28 school year, and require the Department of Finance, beginning on July 1, 2028, to determine the SCFA and SEFA deposit amounts annually for the upcoming school year, as provided. The bill would require the Controller to transfer an amount of money from the General Fund to the SCFA Trust in those amounts. The bill would require any unused funds remaining in an SCFA or SEFA account on June 30 of each school year to be returned to the state for the benefit of elementary and secondary education, upon appropriation by the Legislature. The bill would specify the membership of the SCFA Trust Board and would vest the SCFA Trust Board with certain powers and duties. The bill would establish 2 accounts within the SCFA Trust, the SCFA Trust Program Account and the SCFA Trust Administrative Account, and would continuously appropriate the moneys in the program account to the SCFA Trust Board for purposes of the bill, thereby making an appropriation. The bill would require the Superintendent of Public Instruction to establish a procedure for the parents and legal guardians of eligible students to apply to establish an SCFA or SEFA and submit an executed participation agreement. The bill would authorize the SCFA Trust Board to disburse funds from SCFAs or SEFAs to eligible schools, defined as private full-time day schools accredited by, or, except as provided, awaiting accreditation from, a regional accrediting agency recognized by the state or the United States Department of Education. The bill would specify the procedures for participating eligible schools to receive funds disbursed by the SCFA Trust Board. (2) The Classroom Instructional Improvement and Accountability Act, an initiative approved by the voters as Proposition 98 at the November 8, 1988, statewide general election, amended the California Constitution to, among other things, set forth a formula for computing the minimum amount of revenues that the state is required to appropriate for the support of school districts and community college districts based on one of 3 tests in any given fiscal year, one of which is based on the percentage of General Fund revenues appropriated for school districts and community college districts, respectively, in the 1986–87 fiscal year, and 2 of which are based on, among other things, changes in enrollment. This bill would require the Legislature to recalculate that minimum education funding guarantee by including eligible students not enrolled in a public elementary or secondary school before the operative date of the act in those minimum funding guarantee calculations based on average daily attendance, as provided. The bill would also require the costs of providing SCFA and SEFA deposit amounts for eligible students to be apportioned between the General Fund and the public school district in which those eligible students reside in the same ratio of General Fund and local property tax revenue that would have been used to educate those eligible students in their public school district. (3) The Personal Income Tax Law, in modified conformity with federal law, generally defines "gross income" as income from whatever source derived, except as specifically excluded, and provides various exclusions from gross income for purposes of computing tax liability. This bill would, for taxable years beginning on or after January 1, 2027, exclude from gross income any amounts received as distribution from an SCFA or SEFA, as defined, as part of a participation agreement. Existing law requires a bill authorizing a new tax expenditure to contain, among other things, specific goals, purposes, and objectives the tax expenditure will achieve, detailed performance indicators, and data collection requirements. This bill would include additional information required for any bill authorizing a new tax expenditure. (4) These provisions would become operative on January 1, 2027, and only if Senate Constitutional Amendment ____ of the 2025–26 Regular Session is approved by the voters at the statewide general election on November 4, 2026.
Bill status
failed
1 of 4 stages cleared
Introduction
Jan 2025
Committee Review
Floor Vote
Governor
Introduced Jan 9, 2025
Last action Feb 2, 2026
Maddy AI version diff · 2 comparisons
What changed between versions
01/09/25 - Introduced
→
02/27/25 - Amended Senate
·
1 edit
·
Feb 27, 2025
MINOR
The Senate amendment to SB 64 (School Choice Flex Account Act of 2025) is almost entirely technical and formatting in nature, consisting of line renumbering, page number adjustments, and paragraph reflow across the document. The only substantive text change is a typo correction in the eligible student income threshold provision, where '2030-3031' was corrected to '2030-31'. No policy provisions, funding amounts, eligibility criteria, or structural elements were altered.
TECHNICAL
Corrected a typo in the eligible student definition: the school year reference '2030-3031' was fixed to '2030-31' in subdivision (g)(2) of Section 69995.01, which sets the income threshold for the 2029-30 and 2030-31 school years.
Floor votes
How they voted
No floor votes recorded yet.
Full legislative history
Actions timeline
Total actions
7
Key actions
1
Committee
2
Amendments
1
Mar 19, 2025
Committee
March 19 set for first hearing. Failed passage in committee. (Ayes 2. Noes 5. Page 420.) Reconsideration granted.
upper
Feb 27, 2025
Upper · Passed
From committee with author's amendments. Read second time and amended. Re-referred to Com. on ED.
upper
Jan 29, 2025
Committee
Referred to Coms. on ED. and REV. & TAX.
upper
Jan 9, 2025
Introduced
Introduced. Read first time. To Com. on RLS. for assignment. To print.
upper
1 primary · 0 co-sponsors
Sponsors
Role
Legislator
Party
State
District
P
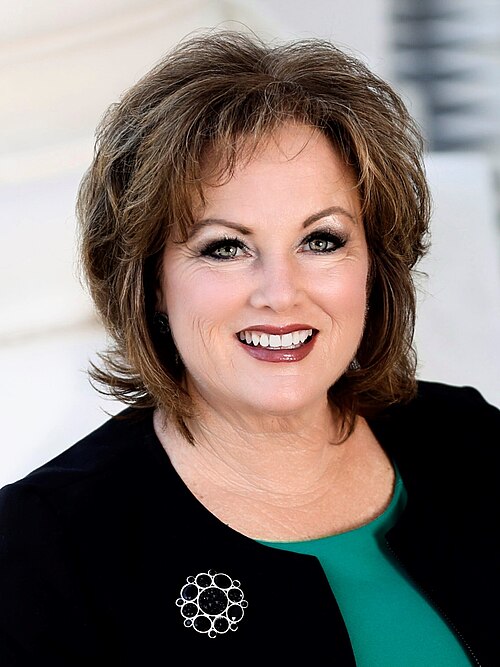
Shannon Grove
RRepublican
Ask Maddy
·
AI policy assistant
Ask Maddy about SB 64
Scope: CA
Hi! I can help you understand SB 64. What would you like to know?
Try one of these
i
Maddy answers using official bill text and legislative records. Always verify before sharing.
Sources cited inline