

Cannabis: taxation: gross receipts.
Summary
The Control, Regulate and Tax Adult Use of Marijuana Act (AUMA) , an initiative measure, authorizes a person who obtains a state license under AUMA to engage in commercial adult-use cannabis activity pursuant to that license and applicable local ordinances. The Medicinal and Adult-Use Cannabis Regulation and Safety Act (MAUCRSA) , among other things, consolidates the licensure and regulation of commercial medicinal and adult-use cannabis activities. Existing law, the Cannabis Tax Law, imposes an excise tax upon purchasers of cannabis or cannabis products sold in this state at the rate of 15% of the gross receipts of any retail sale by a cannabis retailer, and prior to July 1, 2022, a cultivation tax on all harvested cannabis that entered the commercial market, as specified. Existing law provides that taxes imposed under the Cannabis Tax Law are in addition to any other tax imposed by a city or county. Existing law defines "gross receipts" for purposes of the Cannabis Tax Law as it is defined under the Sales and Use Tax Law. Existing sales and use tax laws impose taxes on retailers measured by gross receipts from the sale of tangible personal property sold at retail in this state, or on the storage, use, or other consumption in this state of tangible personal property purchased from a retailer for storage, use, or other consumption in this state, measured by sales price. The Sales and Use Tax Law defines the term "gross receipts" for these purposes to mean the total amount of the sale or lease or rental price of the retail sales of retailers, valued in money, whether received in money or otherwise, as specified, unless an exclusion applies. The Sales and Use Tax Law defines the term "sales price" for these purposes to mean the total amount for which tangible personal property is sold or leased or rented, valued in money, whether received in money or otherwise, as specified, unless an exclusion applies. This bill, beginning January 1, 2024, would exclude from the terms "gross receipts" and "sales price" under the Sales and Use Tax Law the amount of the cannabis excise tax imposed under the Cannabis Tax Law and the amount of any tax imposed by a city or county on the privilege of engaging in commercial cannabis activity, as specified. The bill would also prohibit a city or county from including in the definition of gross receipts, for purposes of any local tax or fee on a licensed cannabis retailer the amount of any cannabis excise tax imposed under the Cannabis Tax Law or any sales and use taxes. By imposing new requirements on local governments with respect to their taxes and fees, the bill would impose a state-mandated local program. The bill would include findings that changes proposed by this bill address a matter of statewide concern rather than a municipal affair and, therefore, apply to all cities, including charter cities. The California Constitution requires the state to reimburse local agencies and school districts for certain costs mandated by the state. Statutory provisions establish procedures for making that reimbursement. This bill would provide that, if the Commission on State Mandates determines that the bill contains costs mandated by the state, reimbursement for those costs shall be made pursuant to the statutory provisions noted above. AUMA authorizes legislative amendment of its provisions with a 23 vote of both houses, without submission to the voters, to further its purposes and intent. This bill would declare that its provisions further the purposes and intent of AUMA. This bill would take effect immediately as a tax levy.
Bill status
passed
3 of 5 stages cleared
Introduction
Feb 2023
Committee Review
Jul 2023
Senate Passage
May 2023
Assembly Passage
Governor
Introduced Feb 14, 2023
Last action Jul 10, 2023
Floor votes · Senate May 30, 2023
How they voted
33–1
Passed · 6 other
Total votes 40
May 30, 2023
D
Democratic31
93% Yea
R
Republican9
44% Yea
Vote distribution
All Yea
All Nay
Mixed
No data
Full legislative history
Actions timeline
Total actions
20
Key actions
6
Committee
7
Amendments
2
Jul 10, 2023
Lower · Passed
July 10 hearing. Held in committee and under submission.
lower
Jun 15, 2023
Committee
Referred to Com. on REV. & TAX.
lower
May 30, 2023
Upper · Passed
Read third time. Passed. (Ayes 33. Noes 1. Page 1353.) Ordered to the Assembly.
upper
May 18, 2023
Upper · Passed
From committee: Do pass. (Ayes 7. Noes 0. Page 1173.) (May 18).
upper
May 10, 2023
Upper · Passed
From committee: Do pass and re-refer to Com. on APPR. (Ayes 6. Noes 0. Page 1043.) (May 10). Re-referred to Com. on APPR.
upper
May 3, 2023
Upper · Passed
From committee with author's amendments. Read second time and amended. Re-referred to Com. on GOV. & F.
upper
May 3, 2023
Committee
May 3 set for first hearing. Failed passage in committee. (Ayes 4. Noes 0. Page 993.) Reconsideration granted.
upper
Mar 29, 2023
Committee
Re-referred to Com. on GOV. & F.
upper
Mar 20, 2023
Upper · Passed
From committee with author's amendments. Read second time and amended. Re-referred to Com. on RLS.
upper
Feb 22, 2023
Committee
Referred to Com. on RLS.
upper
Feb 14, 2023
Introduced
Introduced. Read first time. To Com. on RLS. for assignment. To print.
upper
1 primary · 0 co-sponsors
Sponsors
Role
Legislator
Party
State
District
P
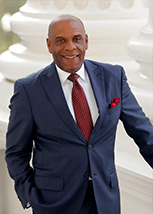
Steve Bradford
DDemocratic
Ask Maddy
·
AI policy assistant
Ask Maddy about SB 512
Scope: CA
Hi! I can help you understand SB 512. What would you like to know?
Try one of these
i
Maddy answers using official bill text and legislative records. Always verify before sharing.
Sources cited inline