

Income tax credits: low-income housing: California Debt Limit Allocation Committee rulemaking.
Summary
(1) Existing federal law prescribes a volume ceiling on the aggregate amount of private activity bonds that may be issued in a state. Existing law creates the California Debt Limit Allocation Committee (CDLAC) for the purpose of administering the volume limit for the state on private activity bonds through an allocation system. Existing law authorizes CDLAC to adopt, amend, or repeal rules and regulations as emergency regulations in accordance with the rulemaking provisions of the Administrative Procedure Act. This bill, instead, would authorize CDLAC to adopt, amend, or repeal rules and regulations without complying with the procedural requirements of the Administrative Procedures Act, except as specified. The bill would make rules and regulations adopted, amended, or repealed by CDLAC effective immediately upon adoption. The bill would provide that these provisions would remain operative only until January 1, 2029, and as of that date would revert to existing law. (2) Existing law establishes a low-income housing tax credit program pursuant to which the California Tax Credit Allocation Committee (CTCAC) provides procedures and requirements for the allocation, in modified conformity with federal law, of state insurance, personal income, and corporation tax credit amounts to qualified low-income housing projects that have been allocated, or qualify for, a federal low-income housing tax credit, and farmworker housing. Existing law limits the total annual amount of the state low-income housing credit for which a federal low-income housing credit is required to the sum of $70,000,000, as increased by any percentage increase in the Consumer Price Index for the preceding calendar year, any unused credit for the preceding calendar years, and the amount of housing credit ceiling returned in the calendar year. Existing law provides for an additional allocation of $500,000,000 in low-income housing tax credits for the 2020 calendar year and up to $500,000,000 for the 2021 calendar year and thereafter. Existing law provides that the additional amount for the 2021 calendar year and thereafter is available only if the Budget Act or related legislation specifies an amount available for allocation. Existing law authorizes CTCAC to allocate up to $200,000,000 of this amount for housing financed by the California Housing Finance Agency (CalHFA) under its Mixed-Income Program. Existing law makes a housing sponsor receiving a nonfederally subsidized allocation ineligible for receipt of this increased housing credit allocation. This bill would, for any calendar year in which CDLAC has declared a competition for the award of tax-exempt bond authority for qualified residential rental projects, authorize CTCAC to allocate some or all of the additional credit amount, other than credits allocated for housing financed by CalHFA under these provisions, to nonfederally subsidized buildings and require CTCAC to allocate the remainder for new buildings, as defined by specified federal law, that are federally subsidized and can begin construction within a reasonable time as determined by the California Tax Credit Allocation Committee. For any calendar year in which CDLAC has not declared a competition for the award of tax-exempt bond authority for qualified residential rental projects, the bill would require a project receiving an award of credits from the additional credit allocation to begin construction within a reasonable time as determined by the California Tax Credit Allocation Committee. The bill would, if there are credits still available after the final allocation round in a calendar year, allow the CTCAC to allocate some or all of the remaining credits for nonfederally subsidized buildings, as specified. (3) For purposes of determining the amount of low-income housing tax credit allocated under the above-described provisions, existing law defines various terms, including the term "applicable percentage." In the case of any qualified low-income building that receives an allocation of the $70,000,000 credit amount available under existing law and meets specified additional criteria, existing law defines "applicable percentage" to mean 30% for each of the first 3 years and 5% for the 4th year. This bill would revise the above-described definition of "applicable percentage" to delete the limitation that the qualified low-income building receive an allocation of the $70,000,000 credit amount available under existing law, thereby applying this definition to any qualified low-income building that meets the above-described criteria. (4) Existing law requires CTCAC to certify to a housing sponsor the amount of credit allocated to the housing sponsor, and requires the taxpayer to attach a copy of this certification to any return claiming the credit. This bill would allow a taxpayer to claim the credit commencing in the year the building is placed in service and the federal credit period commences notwithstanding that CTCAC has not certified the amount of the tax credit. The bill would prohibit the taxpayer from claiming an amount of credit that exceeds the lesser of the applicable percentage multiplied by the qualified basis of the building set forth in the preliminary reservation or the amount of credit for which the project is eligible as certified in the "taxpayer certification," which the bill would define for these purposes as the certification by the certified public accountant of the taxpayer who originally received the preliminary reservation of credits. The bill would authorize CTCAC to review taxpayer certifications, as specified. In the event CTCAC issues a certification that is inconsistent with the taxpayer certification, the bill would require the taxpayer to amend any previously filed tax returns as needed to reflect the credit amount certified by CTCAC. The bill would apply these provisions for taxable years beginning on or after January 1, 2023. This bill would make technical and conforming changes to the low-income housing tax credit program. (5) This bill would include a change in state statute that would result in a taxpayer paying a higher tax within the meaning of Section 3 of Article XIIIA of the California Constitution, and thus would require for passage the approval of 23 of the membership of each house of the Legislature. (6) This bill would incorporate additional changes to Sections 12206, 17058, and 23610.5 of the Revenue and Taxation Code proposed by AB 1439 to be operative only if this bill and AB 1439 are enacted and this bill is enacted last.
Bill status
signed
all 5 stages cleared
Introduction
Jan 2023
Committee Review
Sep 2023
Assembly Passage
May 2023
Senate Passage
Sep 2023
Signed into Law
Oct 2023
Introduced Jan 31, 2023
Signed Oct 11, 2023
Floor votes · Senate Sep 12, 2023 · Assembly May 31, 2023
How they voted
36–0
Passed · 4 other
Total votes 40
Sep 12, 2023
D
Democratic31
96% Yea
R
Republican9
66% Yea
Vote distribution
All Yea
All Nay
Mixed
No data
Full legislative history
Actions timeline
Total actions
30
Key actions
14
Committee
13
Amendments
7
Oct 11, 2023
Signed into law
Approved by the Governor.
legislature
Sep 13, 2023
Lower · Passed
Senate amendments concurred in. To Engrossing and Enrolling. (Ayes 79. Noes 0. Page 3349.).
lower
Sep 12, 2023
Introduced
In Assembly. Concurrence in Senate amendments pending.
lower
Sep 12, 2023
Upper · Passed
Read third time. Passed. Ordered to the Assembly. (Ayes 36. Noes 0. Page 2634.).
upper
Sep 7, 2023
Upper · Passed
Read third time and amended. Ordered to second reading.
upper
Sep 1, 2023
Upper · Passed
From committee: Do pass. (Ayes 6. Noes 0.) (September 1).
upper
Aug 14, 2023
Committee
In committee: Referred to APPR suspense file.
upper
Jul 13, 2023
Upper · Passed
Read second time and amended. Re-referred to Com. on APPR.
upper
Jul 13, 2023
Introduced
From committee: Amend, and do pass as amended and re-refer to Com. on APPR. (Ayes 6. Noes 0.) (July 12).
upper
Jul 6, 2023
Upper · Passed
Measure version as amended on July 3 corrected.
upper
Jul 3, 2023
Introduced
From committee chair, with author's amendments: Amend, and re-refer to committee. Read second time, amended, and re-referred to Com. on GOV. & F.
upper
Jun 21, 2023
Upper · Passed
From committee: Do pass and re-refer to Com. on GOV. & F. (Ayes 10. Noes 0.) (June 20). Re-referred to Com. on GOV. & F.
upper
Jun 14, 2023
Committee
Referred to Coms. on HOUSING and GOV. & F.
upper
May 31, 2023
Lower · Passed
Read third time. Passed. Ordered to the Senate. (Ayes 77. Noes 0. Page 1970.)
lower
May 18, 2023
Lower · Passed
From committee: Do pass. (Ayes 13. Noes 0.) (May 18).
lower
May 10, 2023
Committee
In committee: Set, first hearing. Referred to APPR. suspense file.
lower
Apr 25, 2023
Lower · Passed
From committee: Do pass and re-refer to Com. on APPR. (Ayes 10. Noes 0.) (April 24). Re-referred to Com. on APPR.
lower
Apr 24, 2023
Committee
In committee: Set, first hearing. Referred to REV. & TAX. suspense file.
lower
Apr 19, 2023
Lower · Passed
From committee: Do pass and re-refer to Com. on REV. & TAX. (Ayes 7. Noes 0.) (April 19). Re-referred to Com. on REV. & TAX.
lower
Apr 11, 2023
Lower · Passed
In committee: Hearing postponed by committee.
lower
Apr 10, 2023
Committee
Re-referred to Coms. on H. & C.D. and REV. & TAX. pursuant to Assembly Rule 96.
lower
Feb 9, 2023
Committee
Referred to Coms. on REV. & TAX. and H. & C.D.
lower
Feb 1, 2023
Lower · Passed
From printer. May be heard in committee March 3.
lower
1 primary · 0 co-sponsors
Sponsors
Role
Legislator
Party
State
District
P
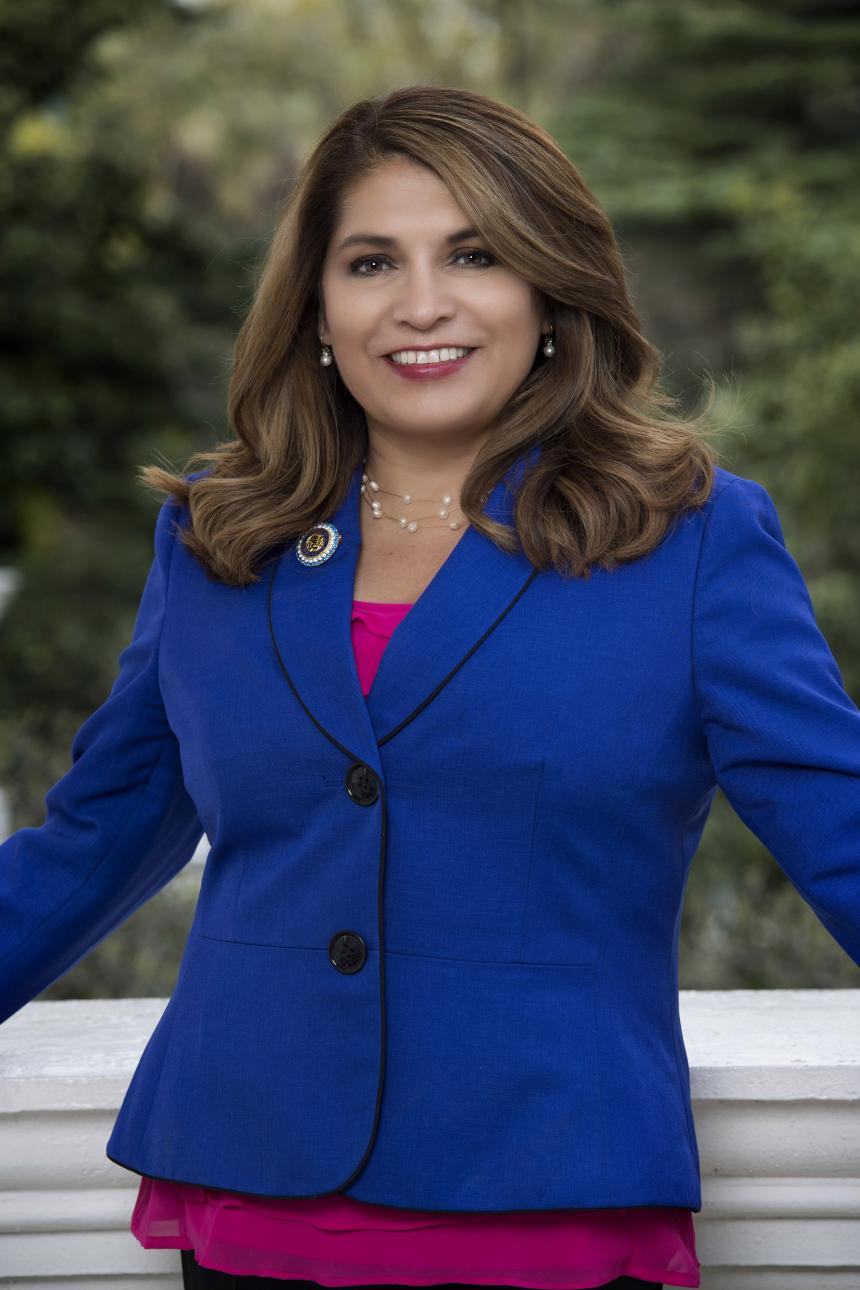
Sharon Quirk-Silva
DDemocratic
Ask Maddy
·
AI policy assistant
Ask Maddy about AB 346
Scope: CA
Hi! I can help you understand AB 346. What would you like to know?
Try one of these
i
Maddy answers using official bill text and legislative records. Always verify before sharing.
Sources cited inline