

Sales and use tax: exemption: medicinal cannabis: donations.
Summary
Existing law, the Medicinal and Adult-Use Cannabis Regulation and Safety Act (MAUCRSA) , among other things, consolidates the licensure and regulation of commercial medicinal and adult-use cannabis activities. Existing sales and use tax laws impose use taxes on the storage, use, or other consumption in this state of tangible personal property purchased from a retailer for storage, use, or other consumption in this state, presumes tangible personal property purchased outside the state that is stored, used, or consumed in this state is purchased for use in this state, and provides various exemptions from those taxes. Existing law exempts from the use tax the storage, use, or other consumption in this state of medicinal cannabis or medicinal cannabis products that are donated, for no consideration, under specified circumstances. Existing law requires the exemption to apply only if the cannabis retailer certifies in writing, as specified, that the medicinal cannabis or medicinal cannabis product will be used as specified. Existing law makes a licensee that uses the donated medicinal cannabis or medicinal cannabis product in some other manner, or for some other purpose, liable for the payment of use tax and subject to having their license suspended. Existing law repeals these provisions 5 years after the specified operative date. This bill would extend these provisions until January 1, 2030. By expanding the scope of the crime of perjury, the bill would impose a state-mandated local program. The Bradley-Burns Uniform Local Sales and Use Tax Law authorizes counties and cities to impose local sales and use taxes in conformity with the Sales and Use Tax Law, and existing laws authorize districts, as specified, to impose transactions and use taxes in accordance with the Transactions and Use Tax Law, which generally conforms to the Sales and Use Tax Law. Amendments to the Sales and Use Tax Law are automatically incorporated into the local tax laws. Existing law requires the state to reimburse counties and cities for revenue losses caused by the enactment of sales and use tax exemptions. This bill would provide that, notwithstanding Section 2230 of the Revenue and Taxation Code, no appropriation is made and the state shall not reimburse any local agencies for sales and use tax revenues lost by them pursuant to this bill. Existing law requires a bill authorizing a new tax expenditure to contain, among other things, specific goals, purposes, and objectives that the tax expenditure will achieve, detailed performance indicators, and data collection requirements. This bill would require the Legislative Analyst's Office, in order to enable the Legislature to determine whether the use tax exemption provided by the bill is meeting, failing to meet, or exceeding a specified goal and objective, to collect certain data regarding the tax exemption from specified entities, and to submit a report containing the data to the Legislature and the Governor annually each year that the tax exemption is in effect. The California Constitution requires the state to reimburse local agencies and school districts for certain costs mandated by the state. Statutory provisions establish procedures for making that reimbursement. This bill would provide that no reimbursement is required by this act for a specified reason. This bill would take effect immediately as a tax levy.
Bill status
signed
all 5 stages cleared
Introduction
Feb 2024
Committee Review
Aug 2024
Assembly Passage
May 2024
Senate Passage
Aug 2024
Signed into Law
Sep 2024
Introduced Feb 14, 2024
Signed Sep 29, 2024
Floor votes · Senate Aug 28, 2024 · Assembly May 22, 2024
How they voted
39–0
Passed · 1 other
Total votes 40
Aug 28, 2024
D
Democratic31
100% Yea
R
Republican9
88% Yea
Vote distribution
All Yea
All Nay
Mixed
No data
Full legislative history
Actions timeline
Total actions
24
Key actions
9
Committee
12
Amendments
1
Sep 29, 2024
Signed into law
Approved by the Governor.
legislature
Aug 28, 2024
Lower · Passed
In Assembly. Ordered to Engrossing and Enrolling.
lower
Aug 28, 2024
Upper · Passed
Read third time. Passed. Ordered to the Assembly. (Ayes 39. Noes 0.).
upper
Aug 15, 2024
Upper · Passed
From committee: Do pass. (Ayes 7. Noes 0.) (August 15).
upper
Aug 5, 2024
Committee
In committee: Referred to APPR suspense file.
upper
Jun 26, 2024
Upper · Passed
From committee: Do pass and re-refer to Com. on APPR. (Ayes 7. Noes 0.) (June 26). Re-referred to Com. on APPR.
upper
Jun 5, 2024
Committee
Referred to Com. on REV. & TAX.
upper
May 22, 2024
Lower · Passed
Read third time. Passed. Ordered to the Senate. (Ayes 72. Noes 0. Page 5489.)
lower
May 16, 2024
Lower · Passed
From committee: Do pass. (Ayes 15. Noes 0.) (May 16).
lower
May 15, 2024
Committee
In committee: Set, first hearing. Referred to APPR. suspense file.
lower
Apr 30, 2024
Lower · Passed
From committee: Do pass and re-refer to Com. on APPR. (Ayes 7. Noes 0.) (April 29). Re-referred to Com. on APPR.
lower
Apr 9, 2024
Committee
Re-referred to Com. on REV. & TAX.
lower
Apr 8, 2024
Introduced
From committee chair, with author's amendments: Amend, and re-refer to Com. on REV. & TAX. Read second time and amended.
lower
Apr 1, 2024
Committee
In committee: Set, first hearing. Referred to REV. & TAX. suspense file.
lower
Mar 4, 2024
Committee
Referred to Com. on REV. & TAX.
lower
Feb 15, 2024
Lower · Passed
From printer. May be heard in committee March 16.
lower
1 primary · 0 co-sponsors
Sponsors
Role
Legislator
Party
State
District
P
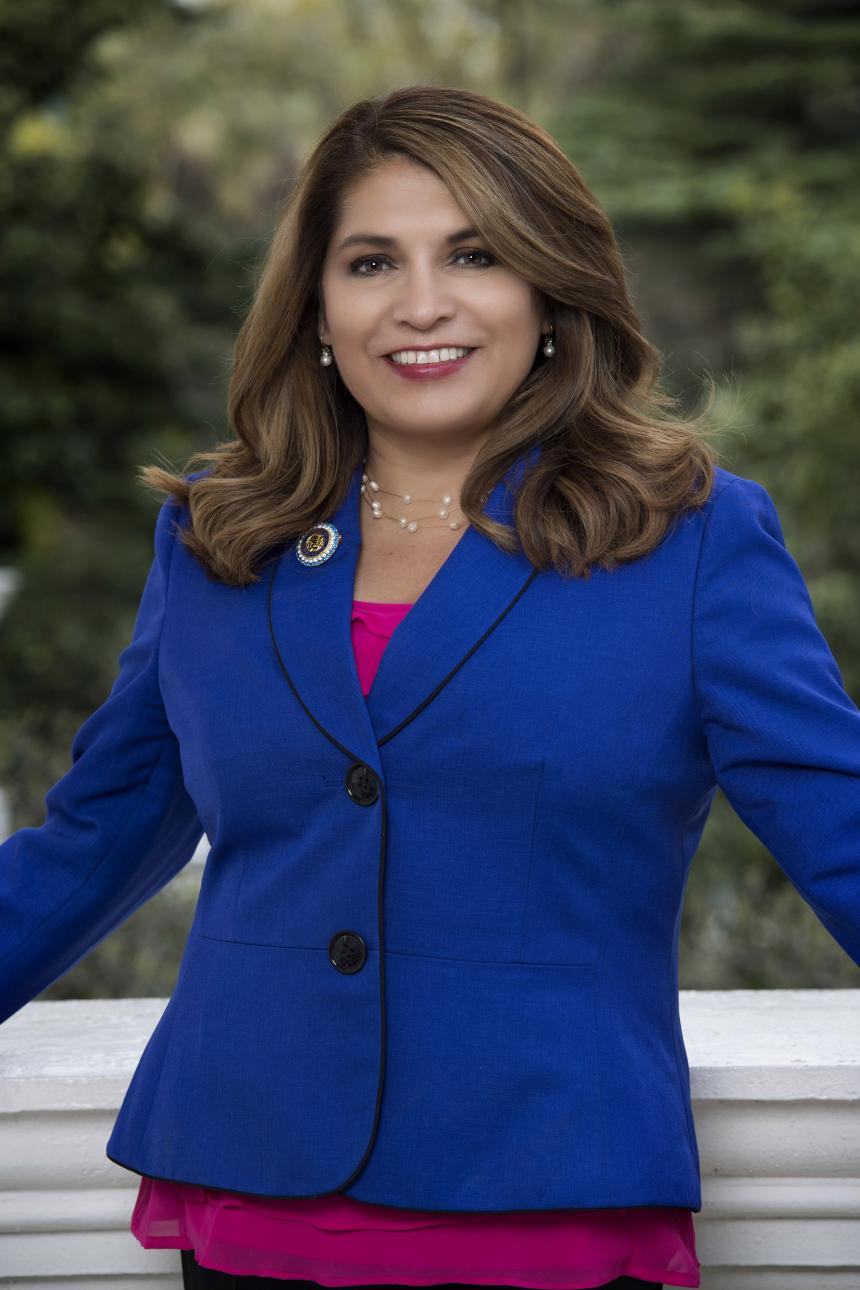
Sharon Quirk-Silva
DDemocratic
Ask Maddy
·
AI policy assistant
Ask Maddy about AB 2555
Scope: CA
Hi! I can help you understand AB 2555. What would you like to know?
Try one of these
i
Maddy answers using official bill text and legislative records. Always verify before sharing.
Sources cited inline