

Change in ownership: nonresidential active solar energy systems: initiative.
Summary
The California Constitution generally limits the maximum rate of ad valorem tax on real property to 1% of the full cash value of the property and defines "full cash value" for these purposes as the appraised value of real property when purchased, newly constructed, or a change in ownership has occurred after the 1975 assessment. Pursuant to constitutional authorization, existing property tax law excludes from the definition of "newly constructed" for these purposes the construction or addition of any active solar energy system, as defined, through the 2023–24 fiscal year. Under existing property tax law, this exclusion remains in effect only until there is a subsequent change in ownership, but an active solar energy system that qualifies for the exclusion before January 1, 2025, will continue to receive the exclusion until there is a subsequent change in ownership. Existing law defines and sets forth parameters for determining a change in ownership for real property. The California Constitution authorizes the Legislature to provide for property taxation of all forms of tangible personal property, shares of capital stock, evidences of indebtedness, and any legal or equitable interest not otherwise exempt. The California Constitution also authorizes the Legislature to classify, by a 23 vote of each house, such personal property for differential taxation or for exemption. This bill would provide that for purposes of the provisions of the California Constitution described above, real property includes improvements, but not personal property. The bill would provide that a nonresidential active solar energy system, as defined, is personal property, not an improvement. The bill would, as provided, exempt a nonresidential active solar energy system constructed or installed prior to January 1, 2025, from taxation until there is a subsequent change in ownership of the nonresidential active solar energy system. The bill would also exempt those nonresidential active solar energy systems from taxation on and after January 1, 2025, until there is a subsequent change in ownership. The bill would provide that change in ownership of a nonresidential active solar energy system occurs if it would have met the parameters for a change in ownership applicable to real property had the system been considered real property instead of personal property. The bill would make its provisions operative on the date that an initiative measure relating to the definition of "full cash value" for commercial and industrial real property, adding a specified section to the California Constitution at the November 3, 2020, statewide general election, becomes effective. The bill would provide that its provisions relating to nonresidential active solar energy systems shall remain inoperative until, and be repealed on, January 1, 2021, if a majority of voters do not approve the initiative. The bill would make conforming changes and make related findings and declarations. By adding to the duties of county assessors when assessing commercial and industrial real property, the bill would impose a state-mandated local program. The California Constitution requires the state to reimburse local agencies and school districts for certain costs mandated by the state. Statutory provisions establish procedures for making that reimbursement. This bill would provide that, if the Commission on State Mandates determines that the bill contains costs mandated by the state, reimbursement for those costs shall be made pursuant to the statutory provisions noted above. Existing law requires the state to reimburse local agencies annually for certain property tax revenues lost as a result of any exemption or classification of property for purposes of ad valorem property taxation. This bill would provide that, notwithstanding those provisions, no appropriation is made and the state shall not reimburse local agencies for property tax revenues lost by them pursuant to the bill. This bill would take effect immediately as a tax levy.
Bill status
signed
all 5 stages cleared
Introduction
Feb 2019
Committee Review
Jul 2020
Senate Passage
May 2019
Assembly Passage
Aug 2020
Signed into Law
Sep 2020
Introduced Feb 20, 2019
Signed Sep 9, 2020
Floor votes · Senate May 23, 2019 · Assembly Aug 3, 2020
How they voted
34–0
Passed
Total votes 34
May 23, 2019
D
Democratic26
100% Yea
R
Republican8
100% Yea
Vote distribution
All Yea
All Nay
Mixed
No data
Full legislative history
Actions timeline
Total actions
27
Key actions
9
Committee
6
Amendments
3
Sep 9, 2020
Signed into law
Approved by the Governor.
legislature
Aug 24, 2020
Upper · Passed
Assembly amendments concurred in. (Ayes 30. Noes 10. Page 4286.) Ordered to engrossing and enrolling.
upper
Aug 3, 2020
Introduced
In Senate. Concurrence in Assembly amendments pending.
upper
Aug 3, 2020
Lower · Passed
Read third time. Passed. (Ayes 56. Noes 12. Page 5059.) Ordered to the Senate.
lower
Jul 27, 2020
Lower · Passed
From committee: Do pass. (Ayes 6. Noes 1.) (July 27).
lower
Jun 6, 2019
Committee
Referred to Coms. on REV. & TAX. and V.A.
lower
May 23, 2019
Upper · Passed
Read third time. Passed. (Ayes 38. Noes 0. Page 1268.) Ordered to the Assembly.
upper
May 17, 2019
Upper · Passed
Read second time and amended. Ordered to second reading.
upper
May 17, 2019
Upper · Passed
From committee: Do pass as amended. (Ayes 6. Noes 0. Page 1097.) (May 16).
upper
Apr 24, 2019
Upper · Passed
From committee: Do pass and re-refer to Com. on APPR. (Ayes 7. Noes 0. Page 807.) (April 23). Re-referred to Com. on APPR.
upper
Mar 27, 2019
Upper · Passed
From committee: Do pass and re-refer to Com. on V.A. (Ayes 7. Noes 0. Page 465.) (March 27). Re-referred to Com. on V.A.
upper
Feb 28, 2019
Committee
Referred to Coms. on GOV. & F. and V.A.
upper
Feb 20, 2019
Introduced
Introduced. Read first time. To Com. on RLS. for assignment. To print.
upper
1 primary · 0 co-sponsors
Sponsors
Role
Legislator
Party
State
District
P
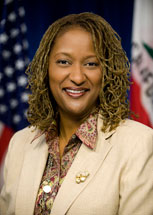
Holly J. Mitchell
DDemocratic
Ask Maddy
·
AI policy assistant
Ask Maddy about SB 364
Scope: CA
Hi! I can help you understand SB 364. What would you like to know?
Try one of these
i
Maddy answers using official bill text and legislative records. Always verify before sharing.
Sources cited inline