

Property taxation: new construction: definition.
Summary
The California Constitution generally limits ad valorem taxes on real property to 1% of the full cash value of that property. For purposes of this limitation, "full cash value" is defined as the assessor's valuation of real property as shown on the 1975–76 tax bill under "full cash value" or, thereafter, the appraised value of that real property when purchased, newly constructed, or a change in ownership has occurred. Existing law defines "newly constructed" and "new construction" to mean any addition to real property since the last lien date and any alteration of land or of any improvement since the last lien date that constitutes a major rehabilitation thereof or that converts the property to a different use. Existing law, where real property has been damaged or destroyed by misfortune or calamity, excludes from the definition of "newly constructed" and "new construction" any timely reconstruction of the real property, or portion thereof, where the property after reconstruction is substantially equivalent to the property prior to damage or destruction. This bill would define the term "substantially equivalent" for purposes of the provisions described above to mean the size of the improvement after reconstruction does not exceed 120% of the size of the improvement prior to damage or destruction or the full cash value of the improvement after reconstruction does not exceed 120% of the full cash value of the improvement prior to damage or destruction. The bill would apply this definition to real property damaged or destroyed by misfortune or calamity on or after January 1, 2017. By imposing new duties upon local government officials, this bill would impose a state-mandated local program. This bill would make legislative findings and declarations regarding the public purpose served by the bill. The California Constitution requires the state to reimburse local agencies and school districts for certain costs mandated by the state. Statutory provisions establish procedures for making that reimbursement. This bill would provide that, if the Commission on State Mandates determines that the bill contains costs mandated by the state, reimbursement for those costs shall be made pursuant to the statutory provisions noted above. Existing law requires the state to reimburse local agencies annually for certain property tax revenues lost as a result of any exemption or classification of property for purposes of ad valorem property taxation. This bill would provide that, notwithstanding those provisions, no appropriation is made and the state shall not reimburse local agencies for property tax revenues lost by them pursuant to the bill.
Bill status
vetoed
4 of 5 stages cleared
Introduction
Feb 2019
Committee Review
Jun 2019
Assembly Passage
May 2019
Senate Passage
Sep 2019
Vetoed
Oct 2019
Introduced Feb 20, 2019
Vetoed Oct 13, 2019
Floor votes · Senate Sep 4, 2019 · Assembly May 22, 2019
How they voted
34–0
Passed
Total votes 34
Sep 4, 2019
D
Democratic26
100% Yea
R
Republican8
100% Yea
Vote distribution
All Yea
All Nay
Mixed
No data
Full legislative history
Actions timeline
Total actions
22
Key actions
10
Committee
9
Amendments
4
Jan 21, 2020
Vetoed
Consideration of Governor's veto stricken from file.
lower
Oct 13, 2019
Vetoed
Vetoed by Governor.
lower
Sep 9, 2019
Lower · Passed
Senate amendments concurred in. To Engrossing and Enrolling. (Ayes 79. Noes 0. Page 3102.).
lower
Sep 5, 2019
Introduced
In Assembly. Concurrence in Senate amendments pending. May be considered on or after September 7 pursuant to Assembly Rule 77.
lower
Sep 4, 2019
Upper · Passed
Read third time. Passed. Ordered to the Assembly. (Ayes 40. Noes 0. Page 2493.).
upper
Aug 30, 2019
Upper · Passed
Read second time and amended. Ordered returned to second reading.
upper
Aug 30, 2019
Upper · Passed
From committee: Amend, and do pass as amended. (Ayes 7. Noes 0.) (August 30).
upper
Jun 24, 2019
Committee
In committee: Referred to APPR. suspense file.
upper
Jun 12, 2019
Upper · Passed
From committee: Do pass and re-refer to Com. on APPR. (Ayes 6. Noes 0.) (June 12). Re-referred to Com. on APPR.
upper
May 29, 2019
Committee
Referred to Com. on GOV. & F.
upper
May 22, 2019
Lower · Passed
Read third time. Passed. Ordered to the Senate. (Ayes 77. Noes 0. Page 1819.)
lower
May 16, 2019
Lower · Passed
From committee: Do pass. (Ayes 18. Noes 0.) (May 16).
lower
Apr 24, 2019
Committee
In committee: Set, first hearing. Referred to APPR. suspense file.
lower
Apr 9, 2019
Lower · Passed
From committee: Do pass and re-refer to Com. on APPR. (Ayes 11. Noes 0.) (April 8). Re-referred to Com. on APPR.
lower
Mar 25, 2019
Lower · Passed
In committee: Hearing for testimony only.
lower
Mar 4, 2019
Committee
Referred to Com. on REV. & TAX.
lower
Feb 21, 2019
Lower · Passed
From printer. May be heard in committee March 23.
lower
1 primary · 10 co-sponsors
Sponsors
Role
Legislator
Party
State
District
P
Jacqui Irwin
DDemocratic
Co
Anna Caballero
DDemocratic
Co
Bill Dodd
DDemocratic
Co
BM
Brian Maienschein
DDemocratic
Co
Christy Smith
DDemocratic
Co
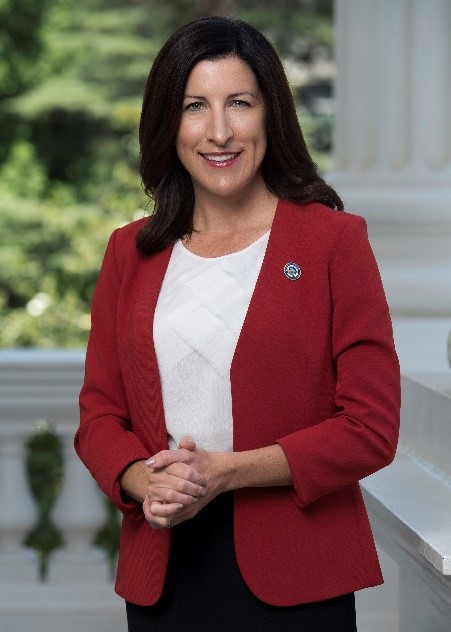
Cottie Petrie-Norris
DDemocratic
Co
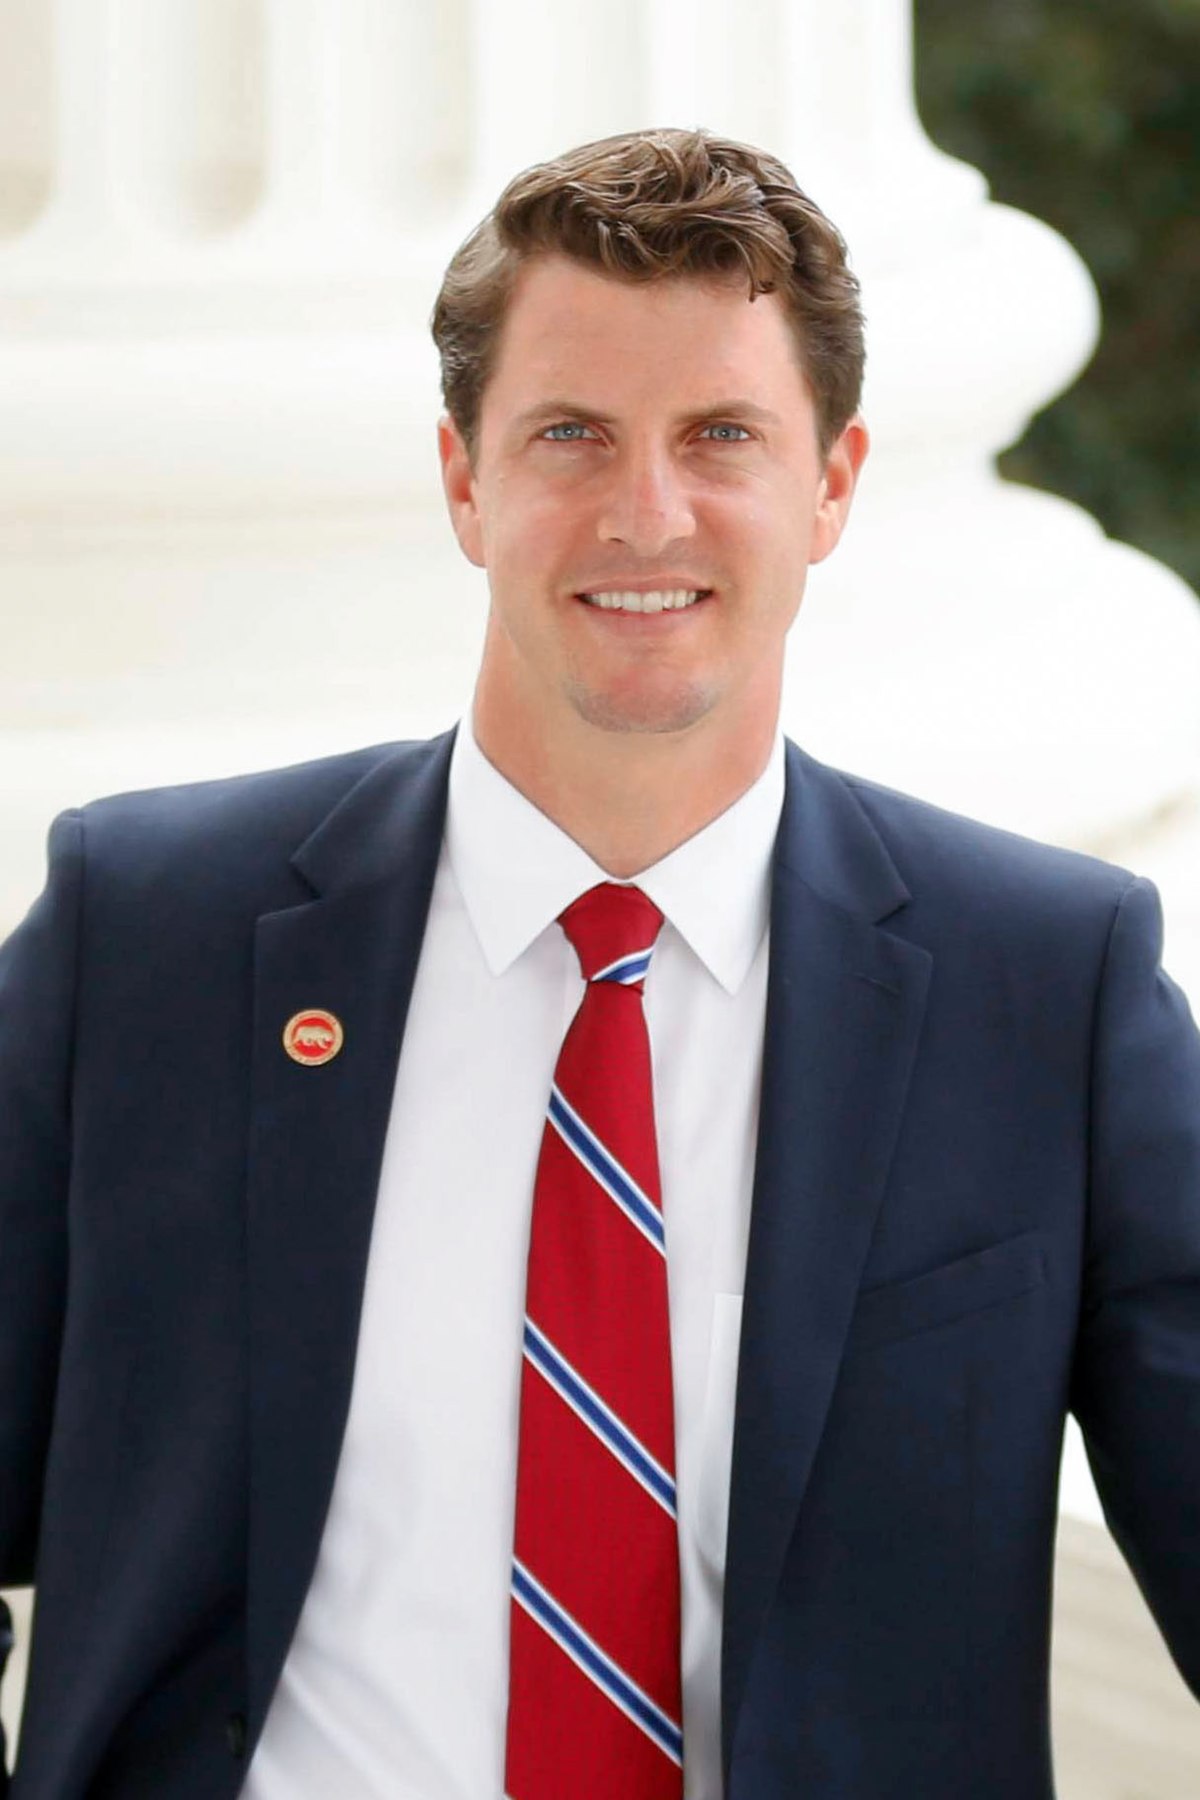
Henry Stern
DDemocratic
Co
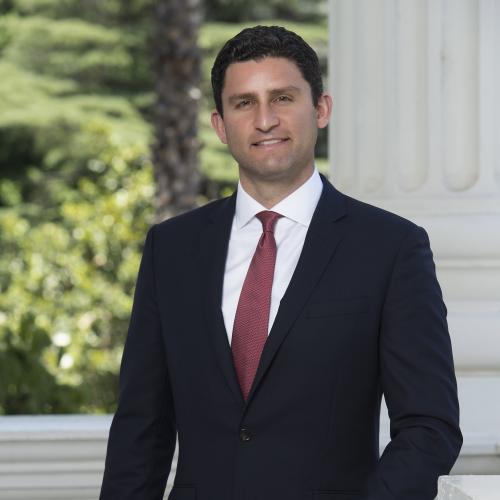
Jesse Gabriel
DDemocratic
Co
Jim Nielsen
RRepublican
Co
JW
Jim Wood
DDemocratic
Co
Tasha Boerner
DDemocratic
Ask Maddy
·
AI policy assistant
Ask Maddy about AB 885
Scope: CA
Hi! I can help you understand AB 885. What would you like to know?
Try one of these
i
Maddy answers using official bill text and legislative records. Always verify before sharing.
Sources cited inline