

Credit services organizations.
Summary
Existing law, the Credit Services Act of 1984, defines and regulates the activities of credit services organizations. Existing law generally defines a credit services organization as a person who, for payment, performs specified credit-related services, such as improving a buyer's credit record and obtaining loans. Existing law requires credit services organizations to obtain a surety bond, as specified, before conducting business and requires that they register with the Attorney General, subject to a fee of $100. Among other things, existing law prohibits a credit services organization from receiving money before full and complete performance of the service the organization has agreed to perform and from failing to perform services agreed upon within 6 months. Existing law requires that credit services be provided pursuant to a written contract, which is required to contain specified statements, and, before the execution of a contract, a credit services organization must provide a prescribed information statement. Existing law requires the contract to contain a notice informing the buyer that the contract can be canceled within 5 days from the date the contract is signed. Existing law authorizes a buyer of services who is injured by a credit services organization's violation of the act, or its breach of contract, to bring an action for damages or injunctive relief, as specified. Existing law also authorizes any person, including a consumer credit reporting agency, to bring an action, as specified, for a violation of the act. This bill would instead require the Department of Business Oversight to register and regulate credit services organizations. The bill would replace the term "buyer" with the term "consumer" for purposes of describing a person utilizing the services of a credit services organization and would prescribe other definitions in this regard. The bill would require a credit services organization to provide a consumer an itemized monthly statement showing each service performed for a consumer, as specified, and would require the organization to perform services agreed upon within 180 days of contracting for those services. The bill would require the information statement and contract to inform the consumer that the contract can be canceled before midnight on the 5th working day after the consumer signs it. The bill would extend prohibitions on counseling a consumer to make untrue statements to other specified parties. Among other things, the bill would prohibit a credit services organization from impersonating a consumer, from failing to identify communications originating from the organization, from submitting a dispute to a consumer credit reporting agency, creditor, debt collector, or debt buyer more than 180 days after the disputed account has been removed, or from failing to provide along with its first written communication to a credit reporting agency or data furnisher sufficient information to investigate a dispute of an account. The bill would also require a consumer credit reporting agency, creditor, debt collector, or debt buyer that knows that a consumer is represented by a credit service organization to communicate with the credit services organization, except as specified. The bill would require a credit services organization to redact specified information in certain written communications. The bill would require a credit services organization to maintain certain information on file for 4 years. The bill would revise information that must be provided before a credit service contract is executed, including a notice regarding the filing of complaints with the Department of Business Oversight or the Attorney General, and would require the Department of Business Oversight to maintain an internet website for this purpose. The bill would revise statements that a credit services contract must include. The bill would prescribe statutory penalties that may be imposed on a credit services organization that willfully and knowingly violates the act. The bill would authorize the Department of Business Oversight to periodically increase the amount of the fee it is authorized to charge for registration of credit services organizations, but the amount of the fee would be prohibited from exceeding that which is reasonable and necessary to satisfy the department's costs in complying with its duties to regulate credit services organizations.
Bill status
passed
3 of 5 stages cleared
Introduction
Feb 2019
Committee Review
Jun 2020
Assembly Passage
Jan 2020
Senate Passage
Governor
Introduced Feb 19, 2019
Last action Jul 14, 2020
Floor votes · Assembly Jan 27, 2020
How they voted
64–0
Passed · 9 other
Total votes 73
Jan 27, 2020
D
Democratic55
94% Yea
I
Independent1
100% Yea
R
Republican17
64% Yea
Vote distribution
All Yea
All Nay
Mixed
No data
Full legislative history
Actions timeline
Total actions
18
Key actions
5
Committee
9
Jun 23, 2020
Committee
Referred to Com. on JUD.
upper
Jan 27, 2020
Lower · Passed
Read third time. Passed. Ordered to the Senate. (Ayes 70. Noes 0. Page 3892.)
lower
Jan 23, 2020
Lower · Passed
From committee: Do pass. (Ayes 16. Noes 0.) (January 23).
lower
Jan 23, 2020
Committee
In committee: Set, first hearing. Referred to APPR. suspense file.
lower
Jan 17, 2020
Committee
Re-referred to Com. on APPR.
lower
Jan 15, 2020
Lower · Passed
From committee: Do pass and re-refer to Com. on APPR. (Ayes 10. Noes 0.) (January 14). Re-referred to Com. on APPR.
lower
Jan 14, 2020
Lower · Passed
From committee: Do pass and re-refer to Com. on P. & C.P. (Ayes 10. Noes 0.) (January 13). Re-referred to Com. on P. & C.P.
lower
Jan 7, 2020
Committee
Re-referred to Com. on B. & F.
lower
Mar 14, 2019
Committee
Referred to Coms. on B. & F. and P. & C.P.
lower
Feb 20, 2019
Lower · Passed
From printer. May be heard in committee March 22.
lower
1 primary · 0 co-sponsors
Sponsors
Role
Legislator
Party
State
District
P
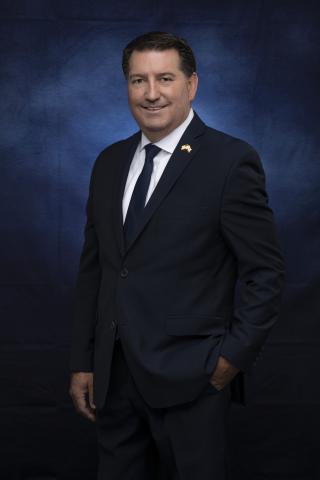
Tim Grayson
DDemocratic
Ask Maddy
·
AI policy assistant
Ask Maddy about AB 699
Scope: CA
Hi! I can help you understand AB 699. What would you like to know?
Try one of these
i
Maddy answers using official bill text and legislative records. Always verify before sharing.
Sources cited inline