

Income taxation: timeliness penalty: abatement.
Summary
Existing law imposes penalties when a taxpayer fails to timely file an income tax return or fails to timely pay the tax due as shown on, or as required to be shown on, the tax return, unless it is shown that the failure is due to reasonable cause and not due to willful neglect. This bill, for taxable years beginning on and after January 1, 2018, would require the Franchise Tax Board, upon request by an individual taxpayer, to abate a failure-to-file or failure-to-pay timeliness penalty if the taxpayer was not previously required to file a California personal income tax return or the Franchise Tax Board has not imposed a timeliness penalty in the year of the request or prior 4 years, the taxpayer has filed all required returns as of the date of the request for abatement, and the taxpayer has paid, or is in a current arrangement to pay, all tax currently due.
Bill status
in committee
1 of 4 stages cleared
Introduction
Feb 2017
Committee Review
Floor Vote
Governor
Introduced Feb 14, 2017
Last action Feb 1, 2018
Floor votes
How they voted
No floor votes recorded yet.
Full legislative history
Actions timeline
Total actions
11
Key actions
2
Committee
3
May 25, 2017
Upper · Passed
May 25 hearing: Held in committee and under submission.
upper
Apr 5, 2017
Upper · Passed
From committee: Do pass and re-refer to Com. on APPR. (Ayes 7. Noes 0. Page 623.) (April 5). Re-referred to Com. on APPR.
upper
Feb 23, 2017
Committee
Referred to Com. on GOV. & F.
upper
Feb 14, 2017
Introduced
Introduced. Read first time. To Com. on RLS. for assignment. To print.
upper
1 primary · 0 co-sponsors
Sponsors
Role
Legislator
Party
State
District
P
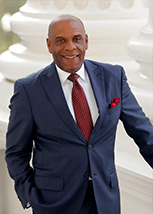
Steve Bradford
DDemocratic
Ask Maddy
·
AI policy assistant
Ask Maddy about SB 375
Scope: CA
Hi! I can help you understand SB 375. What would you like to know?
Try one of these
i
Maddy answers using official bill text and legislative records. Always verify before sharing.
Sources cited inline