

Property taxation: property records: transmission by mail or electronic format.
Summary
Existing property tax law requires, upon request of an assessee of property or designated representative, a county assessor to permit the assessee or representative to inspect or copy all information, documents, and records, other than market data, whether or not required to be kept or prepared by the assessor, relating to the appraisal and the assessment of the assessee's property, and any penalties and interest thereon. This bill would require, upon written request of an assessee or the assessee's designated representative, the assessor to transmit the information, documents, or records by mail, or in electronic format if the information, documents, or records are available in electronic format or have been previously digitized. By imposing a new duty on county assessors, this bill would impose a state-mandated local program. Existing property tax law, if the assessor, pursuant to the request of any party, provides information or records that the assessor is not required by law to prepare or keep, authorizes the county to require that a fee reasonably related to the actual cost of developing and providing that information be paid by the party receiving the information, including developmental and indirect costs. This bill would provide that fees for costs of providing information or records that the assessor is not required by law to prepare or keep do not apply to information, documents, or records requested by the assessee or representative if that information is transmitted in electronic format, except that any developmental or indirect costs to provide that information, such as costs to acquire or compile data that is not required to be kept or prepared by the assessor, may be recovered. Existing property tax law requires each person owning taxable personal property, other than a certain class of manufactured housing, having an aggregate cost of $100,000 or more for any assessment year to file a signed property statement with the assessor. Existing property tax law also requires every person, as required by the county assessor, to make available for examination information or records regarding his or her property or any other personal property located on premises that he or she owns or controls. This bill would require, upon written request of an assessor, the assessee or the assessee's designated representative to transmit the information or records by mail, or in electronic format if the information or records are available in electronic format or have been previously digitized. Existing property tax law requires a person owning, claiming, possessing, or controlling property subject to local assessment to make available at his or her principal place of business, principal location or principal address in California, or at a place mutually agreeable to the county assessor and the person, a true copy of business records relevant to the amount, cost, and value of all property that he or she owns, claims, possesses, or controls within the county. This bill would eliminate the requirement of making a true copy of business records available at a place mutually agreeable to the county assessor and the person, and would require, upon written request of an assessor, that copy business records be transmitted by an assessee or the assessee's designated representative by mail, or electronic format if the business records are available in electronic format or have been previously digitized. This bill would incorporate additional changes to Section 408 of the Revenue and Taxation Code proposed by SB 1172 to be operative only if this bill and SB 1172 are enacted and this bill is enacted last. The California Constitution requires the state to reimburse local agencies and school districts for certain costs mandated by the state. Statutory provisions establish procedures for making that reimbursement. This bill would provide that no reimbursement is required by this act for a specified reason.
Bill status
signed
all 5 stages cleared
Introduction
Feb 2018
Committee Review
Aug 2018
Assembly Passage
May 2018
Senate Passage
Aug 2018
Signed into Law
Sep 2018
Introduced Feb 14, 2018
Signed Sep 30, 2018
Floor votes · Senate Aug 28, 2018 · Assembly May 10, 2018
How they voted
24–9
Passed · 2 other
Total votes 35
Aug 28, 2018
D
Democratic24
100% Yea
R
Republican11
81% Nay
Vote distribution
All Yea
All Nay
Mixed
No data
Full legislative history
Actions timeline
Total actions
26
Key actions
10
Committee
8
Amendments
4
Sep 30, 2018
Signed into law
Approved by the Governor.
legislature
Aug 29, 2018
Lower · Passed
Senate amendments concurred in. To Engrossing and Enrolling. (Ayes 54. Noes 25. Page 6893.).
lower
Aug 28, 2018
Senate · Passed
Senate Vote: pass (24-9-2)
senate
Aug 28, 2018
Introduced
In Assembly. Concurrence in Senate amendments pending. May be considered on or after August 30 pursuant to Assembly Rule 77.
lower
Aug 20, 2018
Upper · Passed
Read third time and amended. Ordered to second reading.
upper
Jun 25, 2018
Upper · Passed
From committee: Be ordered to second reading pursuant to Senate Rule 28.8.
upper
Jun 13, 2018
Upper · Passed
From committee: Do pass and re-refer to Com. on APPR. (Ayes 5. Noes 1.) (June 13). Re-referred to Com. on APPR.
upper
May 24, 2018
Committee
Referred to Com. on GOV. & F.
upper
May 10, 2018
Assembly · Passed
Assembly Vote: pass (46-19-7)
assembly
May 1, 2018
Lower · Passed
From committee: Amend, and do pass as amended. (Ayes 7. Noes 2.) (April 30).
lower
Apr 23, 2018
Lower · Passed
In committee: Set, first hearing. Hearing canceled at the request of author.
lower
Mar 20, 2018
Committee
Re-referred to Com. on REV. & TAX.
lower
Mar 19, 2018
Introduced
From committee chair, with author's amendments: Amend, and re-refer to Com. on REV. & TAX. Read second time and amended.
lower
Mar 15, 2018
Committee
Referred to Com. on REV. & TAX.
lower
Feb 15, 2018
Lower · Passed
From printer. May be heard in committee March 17.
lower
1 primary · 0 co-sponsors
Sponsors
Role
Legislator
Party
State
District
P
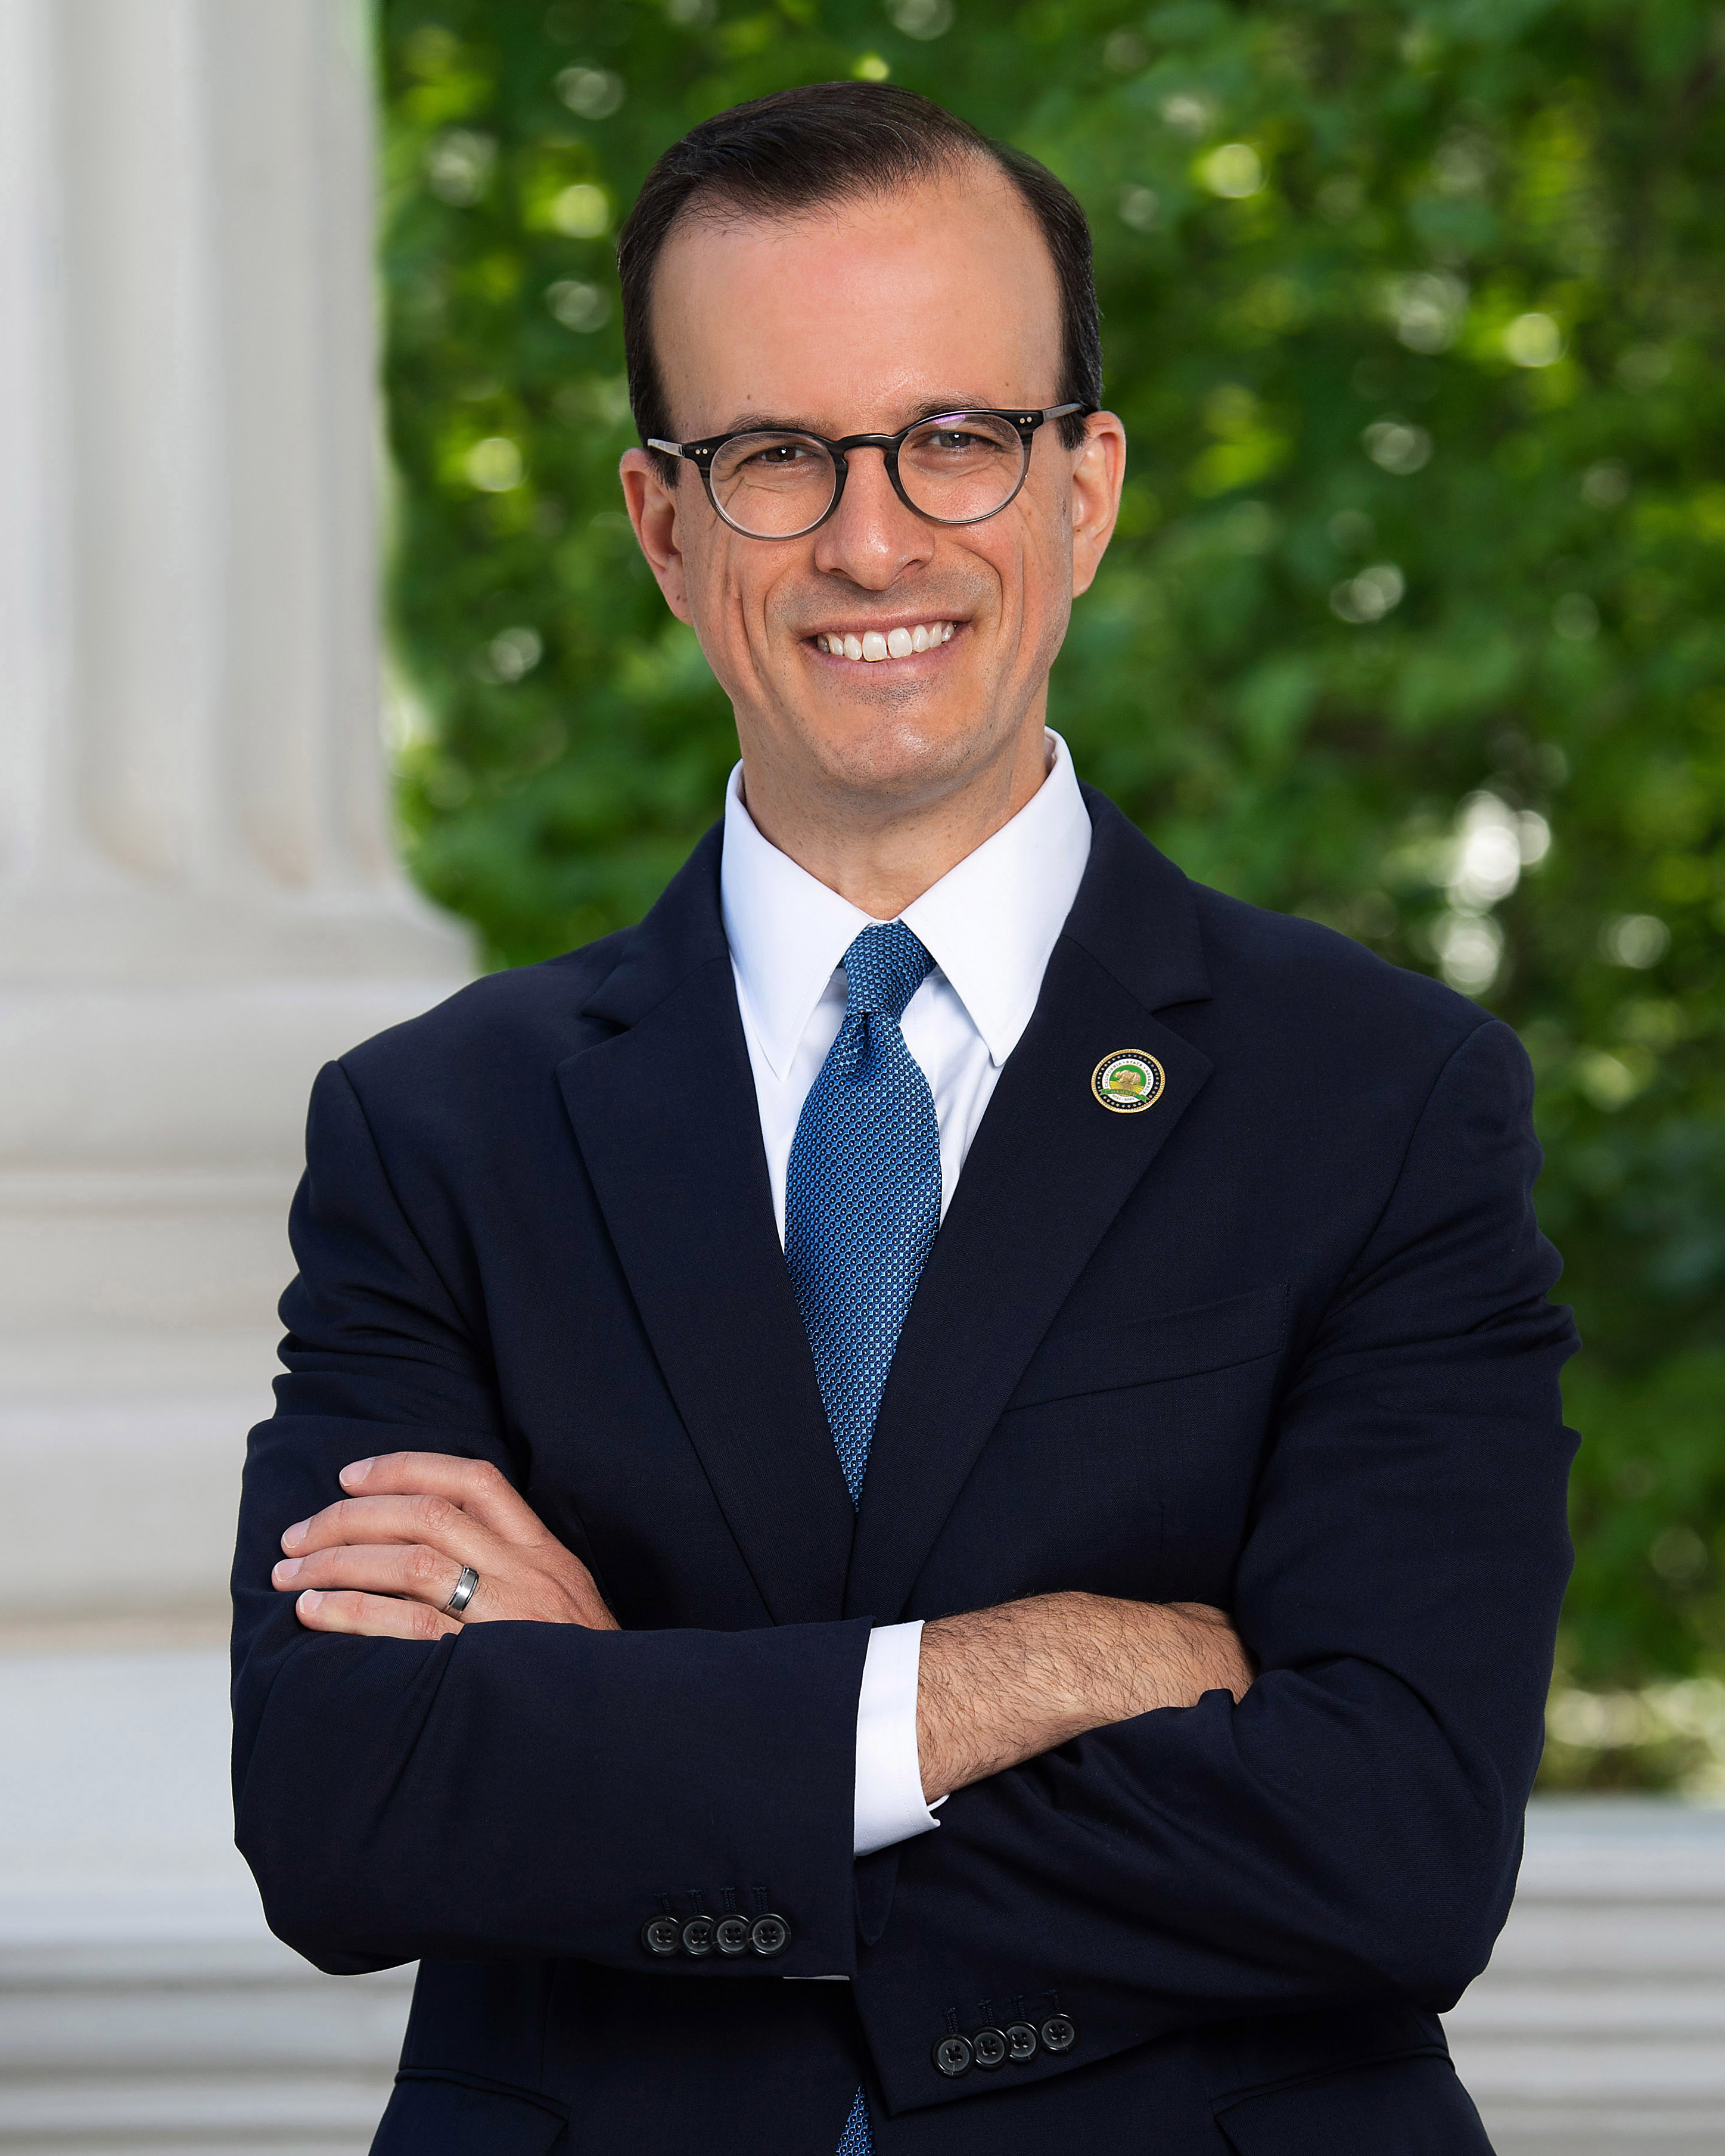
Marc Berman
DDemocratic
Ask Maddy
·
AI policy assistant
Ask Maddy about AB 2425
Scope: CA
Hi! I can help you understand AB 2425. What would you like to know?
Try one of these
i
Maddy answers using official bill text and legislative records. Always verify before sharing.
Sources cited inline