

Property tax postponement.
Summary
(1) Existing law authorizes the Controller, upon approval of a claim for the postponement of ad valorem property taxes, to directly pay a county tax collector for the property taxes owed by the claimant, as provided. Existing law establishes the Senior Citizens and Disabled Citizens Property Tax Postponement Fund and continuously appropriates moneys in the fund to the Controller for specified purposes, including disbursements relating to the postponement of property taxes pursuant to the Property Tax Postponement Law. Existing law requires the Controller to, on June 30, 2018, and on June 30 each year thereafter, transfer any moneys in the fund in excess of $15,000,000 to the General Fund. This bill would eliminate the requirement that the Controller transfer any moneys in the fund in excess of $15,000,000 to the General Fund. The bill would authorize the Director of Finance, upon determination by the Controller that there are insufficient moneys in the fund to cover the cost of all approved claims for the postponement of property taxes, to authorize a transfer from the General Fund to the Senior Citizens and Disabled Citizens Property Tax Postponement Fund in an amount necessary to pay those claims, as specified. By authorizing the expenditure of additional General Fund moneys for the purpose of the property tax postponement program, this bill would make an appropriation. (2) Existing law requires that all sums paid for the postponement of property taxes be secured by a lien in favor of the state. In the case of a lien on real property for this purpose, existing law requires, among other things, the recorder for the county in which the real property is subject to the lien to provide a copy of the notice of lien to the county tax collector. This bill would additionally require the county recorder to provide a copy of the notice of lien to the county assessor. (3) Existing law establishes a formula for calculating the interest on a payment made by the Controller for postponed property taxes from the time a payment is made. Under existing law, for purposes of this provision, a payment is deemed to be made at the time an electronic funds transfer is made by the Controller to the tax collector or the delinquency date of the respective tax installment, whichever is later. Existing law, in the event of willful neglect, authorizes an electronic funds transfer for that current fiscal year to be used to pay delinquent taxes only if accompanied by sufficient amounts to pay all of the delinquent penalties, costs, fees, and interest. Existing law, if a denial of a claim for postponement is reversed on appeal, requires the Controller to electronically transfer funds to the county. This bill would instead deem a payment to be made at the time a payment is made by the Controller to the tax collector or the delinquency date of the respective tax installment, whichever is later. The bill would instead authorize a payment from the Controller to be used to pay delinquent taxes under the circumstances described above. The bill would eliminate the requirement that funds be transferred electronically if a denial of a claim for postponement is reversed on appeal. The bill would also make various conforming changes. (4) Existing law requires the Controller to reduce the amount of the obligation secured by the lien against the real property by the amount of any payments received for that purpose and by specified amounts paid by the Franchise Tax Board or by certain other authorized amounts. This bill would require that payments received for the reduction of the obligation be applied first to any interest due on the loan, 2nd to the principal property tax amount, and finally, if there is any remaining balance, to administrative fees. (5) Existing law authorizes recordation of certain documents, including a release, discharge, or subordination of a lien for postponed property taxes, without acknowledgment, certificate of acknowledgment, or further proof. This bill would delete the reference to the subordination of a lien for postponed property taxes from the above-described list of documents that may be recorded without acknowledgment, certificate of acknowledgment, or further proof. (6) Existing law requires, with respect to a claimant whose property taxes are paid by a lender from an impound, trust, or other specified type of account, the tax collector to notify the auditor of the claimant's name and address, and the duplicate amount of money the Controller transferred to the tax collector via an electronic fund transfer. Existing law requires the county auditor, treasurer, or disbursing officer to send a check, in the amount of money based on the electronic transfer by the Controller, to the Controller within 60 days of the replicated payment. This bill would require the county tax collector to notify the auditor, as described above, upon receipt of the payment by the Controller. The bill would require the tax collector to maintain a record of the fact that taxes on the property have been postponed and, in the case of the secured roll, authorize entry of this information in that portion of the roll which has been designated for tax default information. The bill would require the county auditor, treasurer, or disbursing officer to refund a replicated payment to the claimant, instead of the Controller. (7) Existing law, upon receipt of a "notice of lien for postponed property taxes" from the Controller, requires the tax collector or the assessor, whichever is applicable, to immediately enter on the assessment records applicable to the property the fact that the taxes on the property have been postponed and the Controller's identification number and to notify the Controller of a subsequent change in ownership status, as provided. This bill would instead require the assessor to maintain a record of the fact that the taxes on the property have been postponed and the Controller's identification number and to notify the Controller as described above. (8) Existing law requires, for purposes of the Gonsalves-Deukmejian-Petris Senior Citizens Property Tax Assistance Law, that all losses and nonexpenses be converted to zero for the purpose of determining whether the homeowner meets the property tax postponement requirement. This bill would instead require that all losses and nonexpenses be converted to zero, as specified above, for the purposes of the Property Tax Postponement Law. (9) Existing law requires that a claimant for property tax postponement, generally, be an individual who is a member of the household, is either an owner-occupant, tenant stockholder occupant, or possessory interestholder occupant of the residential dwelling as to which postponement is claimed, and is either 62 years of age or older, blind, or disabled. With respect to blind and disabled claimants, existing law requires that the claimant be blind or disabled, as specified, at the time of application or on December 10 of the fiscal year for which postponement is claimed, whichever is earlier. This bill would instead require, for blind and disabled claimants, that the claimant be blind or disabled at the time of application or on February 10 of the fiscal year for which postponement is claimed. (10) Existing law requires that a claim for postponement of property taxes be for the residential dwelling, defined generally as the principal place of residence of the claimant and so much of the land surrounding it as is reasonably necessary for the use of the dwelling as a home that is owned by the claimant alone or by the claimant and other specified individuals. Existing law authorizes an applicant, defined as including a public agency, an entity acting on behalf of and with the written consent of a public agency, or a financial institution for specified purposes, to assist property owners in financing the installation of distributed generation renewable energy sources, electric vehicle charging infrastructure, or energy or water efficiency improvements through the issuance of Property Assessed Clean Energy (PACE) bonds that are secured by a voluntary contractual assessment on property or a special tax on property. This bill would exclude from a residential dwelling eligible for the property tax postponement program any residential dwelling that is subject to a PACE bond. (11) This bill would make various technical changes related to the property tax postponement program, including updating statutory references to the Senior Citizens and Disabled Citizens Property Tax Postponement Fund and deleting obsolete references to certificates of eligibility and postponement for mobilehomes. (12) This bill would incorporate additional changes to Section 20583 of the Revenue and Taxation Code proposed by SB 909 that would become operative if this bill and SB 909 are enacted and this bill is enacted last. (13) By changing the duties of local officials with respect to the administration of the property tax postponement program, this bill would impose a state-mandated local program. The California Constitution requires the state to reimburse local agencies and school districts for certain costs mandated by the state. Statutory provisions establish procedures for making that reimbursement. This bill would provide that, if the Commission on State Mandates determines that the bill contains costs mandated by the state, reimbursement for those costs shall be made pursuant to these statutory provisions.
Bill status
vetoed
4 of 5 stages cleared
Introduction
Feb 2016
Committee Review
Aug 2016
Assembly Passage
Jun 2016
Senate Passage
Aug 2016
Vetoed
Sep 2016
Introduced Feb 12, 2016
Vetoed Sep 21, 2016
Floor votes · Senate Aug 22, 2016 · Assembly Jun 3, 2016
How they voted
33–0
Passed
Total votes 33
Aug 22, 2016
D
Democratic23
100% Yea
R
Republican10
100% Yea
Vote distribution
All Yea
All Nay
Mixed
No data
Full legislative history
Actions timeline
Total actions
29
Key actions
7
Committee
12
Amendments
5
Sep 21, 2016
Vetoed
Vetoed by Governor.
lower
Aug 25, 2016
Lower · Passed
Senate amendments concurred in. To Engrossing and Enrolling. (Ayes 79. Noes 0. Page 6290.).
lower
Aug 23, 2016
Introduced
In Assembly. Concurrence in Senate amendments pending. May be considered on or after August 25 pursuant to Assembly Rule 77.
lower
Aug 22, 2016
Senate · Passed
Senate Vote: pass (33-0)
senate
Aug 11, 2016
Upper · Passed
From committee: Do pass. (Ayes 7. Noes 0.) (August 11).
upper
Aug 1, 2016
Committee
In committee: Referred to APPR. suspense file.
upper
Jun 22, 2016
Committee
From committee: Do pass and re-refer to Com. on APPR. (Ayes 6. Noes 0.) (June 22). Re-referred to Com. on APPR.
upper
Jun 15, 2016
Committee
From committee chair, with author's amendments: Amend, and re-refer to committee. Read second time, amended, and re-referred to Com. on GOV. & F.
upper
Jun 9, 2016
Committee
Referred to Com. on GOV. & F.
upper
Jun 3, 2016
Assembly · Passed
Assembly Vote: pass (69-0-2)
assembly
May 27, 2016
Lower · Passed
Read second time and amended. Ordered returned to second reading.
lower
May 27, 2016
Introduced
From committee: Amend, and do pass as amended. (Ayes 20. Noes 0.) (May 27).
lower
May 4, 2016
Committee
In committee: Set, first hearing. Referred to APPR. suspense file.
lower
Apr 28, 2016
Committee
Re-referred to Com. on APPR.
lower
Apr 27, 2016
Lower · Passed
Read second time and amended.
lower
Apr 26, 2016
Introduced
From committee: Amend, and do pass as amended and re-refer to Com. on APPR. (Ayes 9. Noes 0.) (April 18).
lower
Apr 18, 2016
Committee
In committee: Set, first hearing. Referred to REV. & TAX. suspense file.
lower
Apr 7, 2016
Committee
From committee: Do pass and re-refer to Com. on REV. & TAX. (Ayes 9. Noes 0.) (April 6). Re-referred to Com. on REV. & TAX.
lower
Feb 25, 2016
Committee
Referred to Coms. on L. GOV. and REV. & TAX.
lower
Feb 16, 2016
Lower · Passed
From printer. May be heard in committee March 17.
lower
1 primary · 2 co-sponsors
Sponsors
Role
Legislator
Party
State
District
P
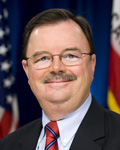
Richard Gordon
DDemocratic
Co
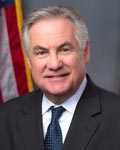
Jim Patterson
RRepublican
Co
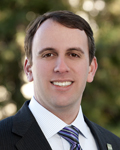
Marc Levine
DDemocratic
Ask Maddy
·
AI policy assistant
Ask Maddy about AB 1952
Scope: CA
Hi! I can help you understand AB 1952. What would you like to know?
Try one of these
i
Maddy answers using official bill text and legislative records. Always verify before sharing.
Sources cited inline