

Insurance: special assessments.
Summary
(1) Existing law, until January 1, 2015, imposes on an insurer a $0.30 special purpose assessment on each vehicle insured under an insurance policy issued in this state by the insurer. Existing law specifies that $0.20 of each $0.30 special purpose assessment shall be used to fund specified consumer service functions of the Department of Insurance relating to motor vehicle insurance. Existing law further specifies that the remaining $0.10 of each $0.30 special purpose assessment shall be used to fund the improvement of certain consumer functions of the department. This bill would revise and recast those provisions, delete the date of repeal, and require a special purpose assessment of $0.25, commencing July 1, 2014, and until January 1, 2016, and not exceeding $0.25 thereafter, on each vehicle insured under an insurance policy issued in this state by the insurer. The bill would also specify that, upon appropriation, 23 of the special purpose assessment be used for the purpose of funding the consumer service functions of the department related to regulating automobile insurers, as provided, and 13 of the special purpose assessment be used for the purpose of improving consumer functions of the department, related to regulating automobile insurers, as specified. The bill would authorize the department, upon appropriation by the Legislature, to use up to $0.05 of the $0.25 special purpose assessment revenues collected to notify insurers and other members of the public about the existence of any low-cost automobile insurance program. (2) Existing law provides that each insurer doing business in this state shall pay an annual special purpose assessment to be determined by the Insurance Commissioner, but not to exceed $0.50 annually for each vehicle insured under an insurance policy the insurer issues in this state, in order to fund the Fraud Division and the Organized Automobile Fraud Activity Interdiction Program. Under existing law, of the funds collected, 42.5% are required to be distributed to district attorneys, 42.5% are required to be distributed to the department's Fraud Division, and 15% are required to be distributed to the Department of the California Highway Patrol, to be used as provided. Existing law provides that this assessment be repealed on January 1, 2015. This bill would revise and recast those provisions, delete the date of repeal, and make the distribution of funds by the commissioner upon appropriation by the Legislature. (3) Existing law creates the Life and Annuity Consumer Protection Fund as a special account within the Insurance Fund, and, until January 1, 2015, requires each insurer admitted to transact insurance in this state to pay a fee determined by the commissioner, not to exceed $1, for each individual life insurance policy and each individual annuity product that it issues to a resident of this state with a value of $15,000 or more. If an insurer elects to charge the purchaser of a life insurance policy or annuity product this fee, the fee is required to be set forth as a separate charge in the contract schedule or premium notice. The moneys in the Life and Annuity Consumer Protection Fund are to be distributed, as provided, and are required to be used exclusively for the purpose of protecting consumers of life insurance and annuity products in this state. Existing law requires that 50% of the moneys in the fund be distributed within the department for functions related to individual life insurance and annuity products, including, but not limited to, educating consumers in all aspects of life insurance and annuity products, consumer protection, purchasing and using insurance and annuity products, claim filing, benefit delivery, and dispute resolution. This bill would revise and recast those provisions, delete the date of repeal, and require that the moneys distributed by the commissioner, upon appropriation by the Legislature, fund the reasonable costs incurred in regulating entities transacting life insurance and annuity products in this state. The bill would delete the requirement that each individual life insurance policy and each individual annuity product have a value of $15,000 or more in order for the special assessment to apply. The bill would also require that instead of consumer education, the moneys in the fund distributed within the department for functions related to individual life insurance and annuity products be used to disseminate information to insurers, insureds, and others regarding the applicable regulation of life insurance and annuity products, including consumer protection, purchasing and using insurance and annuity products, claim filing, benefit delivery, and dispute resolution. (4) Existing law requires the Insurance Commissioner to, on or before the first day of August in each year, make a report to the Governor, the Legislature, and to the committees of the Senate and Assembly having jurisdiction over insurance containing specified information, including the condition of the insurance business and interests in this state. This bill would additionally require the annual report to contain information pertaining to consumer complaints, investigations, administrative and regulatory cases pertaining to automobile insurance, and revenue and expenditures relating to automobile insurance policy assessments, as specified.
Bill status
signed
all 5 stages cleared
Introduction
Feb 2013
Committee Review
Sep 2013
Senate Passage
May 2013
Assembly Passage
Sep 2013
Signed into Law
Sep 2013
Introduced Feb 21, 2013
Signed Sep 24, 2013
Floor votes · Senate May 30, 2013 · Assembly Sep 4, 2013
How they voted
34–1
Passed
Total votes 35
May 30, 2013
D
Democratic26
100% Yea
R
Republican9
88% Yea
Vote distribution
All Yea
All Nay
Mixed
No data
Full legislative history
Actions timeline
Total actions
30
Key actions
12
Committee
12
Amendments
2
Sep 24, 2013
Signed into law
Approved by the Governor.
legislature
Sep 6, 2013
Upper · Passed
Assembly amendments concurred in. (Ayes 37. Noes 0. Page 2172.) Ordered to engrossing and enrolling.
upper
Sep 5, 2013
Introduced
In Senate. Concurrence in Assembly amendments pending.
upper
Sep 4, 2013
Assembly · Passed
Assembly Vote: pass (60-1-2)
assembly
Aug 30, 2013
Lower · Passed
From committee: Do pass. (Ayes 16. Noes 0.) (August 30).
lower
Aug 14, 2013
Committee
Set, first hearing. Referred to APPR. suspense file.
lower
Jul 2, 2013
Lower · Passed
Read second time and amended. Re-referred to Com. on APPR.
lower
Jul 1, 2013
Lower · Passed
From committee: Do pass as amended and re-refer to Com. on APPR. (Ayes 11. Noes 0.) (June 26).
lower
Jun 18, 2013
Lower · Passed
From committee with author's amendments. Read second time and amended. Re-referred to Com. on INS.
lower
Jun 17, 2013
Committee
Referred to Com. on INS.
lower
May 30, 2013
Senate · Passed
Senate Vote: pass (34-1)
senate
May 23, 2013
Upper · Passed
From committee: Do pass. (Ayes 7. Noes 0. Page 1015.) (May 23).
upper
Apr 24, 2013
Upper · Passed
From committee: Do pass and re-refer to Com. on APPR. (Ayes 9. Noes 0. Page 662.) (April 24). Re-referred to Com. on APPR.
upper
Apr 17, 2013
Upper · Passed
From committee with author's amendments. Read second time and amended. Re-referred to Com. on INS.
upper
Apr 11, 2013
Committee
Re-referred to Com. on INS.
upper
Apr 8, 2013
Upper · Passed
From committee with author's amendments. Read second time and amended. Re-referred to Com. on RLS.
upper
Mar 11, 2013
Committee
Referred to Com. on RLS.
upper
1 primary · 0 co-sponsors
Sponsors
Role
Legislator
Party
State
District
P
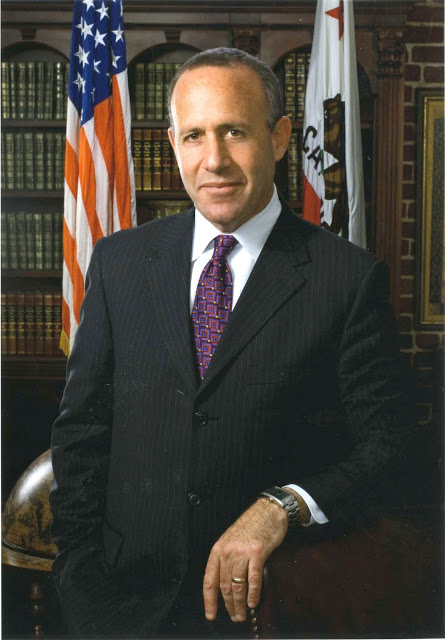
Darrell Steinberg
DDemocratic
Ask Maddy
·
AI policy assistant
Ask Maddy about SB 476
Scope: CA
Hi! I can help you understand SB 476. What would you like to know?
Try one of these
i
Maddy answers using official bill text and legislative records. Always verify before sharing.
Sources cited inline