

Relating to: changes to the low-income housing tax credit. (FE)
AB 976 clarifies how tax credits for low-income housing projects are claimed by business entities. It modifies rules so partnerships, limited liability companies, and tax-option corporations cannot claim the credit directly; instead, their members or shareholders (including insurers who are part of such entities) may claim it based on the entity's eligible costs. The bill requires entities to calculate and distribute credit amounts to members/shareholders, with specific allocation rules for ownership interests or written agreements. It directly affects housing developers, investors, and insurers involved in low-income housing projects financed through tax-exempt bonds in the state. The changes standardize credit allocation across multiple tax code sections without altering eligibility or credit amounts.
Bill status
failed
1 of 4 stages cleared
Introduction
Jan 2026
Committee Review
Floor Vote
Governor
Introduced Jan 30, 2026
Last action Mar 23, 2026
Floor votes
How they voted
No floor votes recorded yet.
Full legislative history
Actions timeline
Total actions
7
Key actions
0
Committee
0
Jan 30, 2026
Introduced
Introduced by Representatives Doyle, Johnson, Arney, Bare, Brown, DeSmidt, Emerson, Fitzgerald, Goodwin, Hysell, Joers, Kirsch, Mayadev, Miresse, Moore Omokunde, Neubauer, Palmeri, Prado, Roe, Sheehan, Sinicki, Snodgrass, Spaude, Stubbs, Subeck, Taylor, Andraca, Haywood, Stroud, Tenorio, Udell and Vining;
cosponsored by Senators Spreitzer, Wall, Dassler-Alfheim, Ratcliff, Roys, Smith, Carpenter, Hesselbein, Larson and Wirch
lower
32 primary · 0 co-sponsors
Sponsors
Role
Legislator
Party
State
District
P
Alex Joers
DDemocratic
P
Andrew Hysell
DDemocratic
P
Angela Stroud
DDemocratic
P
Angelito Tenorio
DDemocratic
P
Ann Roe
DDemocratic
P
Ben DeSmidt
DDemocratic
P
Brienne Brown
DDemocratic
P
Christine Sinicki
DDemocratic
P
Deb Andraca
DDemocratic
P
Greta Neubauer
DDemocratic
P
Joan Fitzgerald
DDemocratic
P
Jodi Emerson
DDemocratic
P
Joe Sheehan
DDemocratic
P
Kalan Haywood
DDemocratic
P
Karen Kirsch
DDemocratic
P
Lee Snodgrass
DDemocratic
P
Lisa Subeck
DDemocratic
P
Lori Palmeri
DDemocratic
P
Margaret Arney
DDemocratic
P
Mike Bare
DDemocratic
P
Priscilla Prado
DDemocratic
P
Randy Udell
DDemocratic
P
Renuka Mayadev
DDemocratic
P
Robyn Vining
DDemocratic
P
Russell Goodwin
DDemocratic
P
Ryan Spaude
DDemocratic
P
Sequanna Taylor
DDemocratic
P
Shelia Stubbs
DDemocratic
P
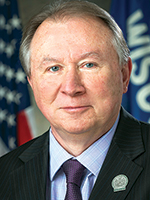
Steve Doyle
DDemocratic
P
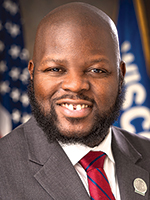
Supreme Moore Omokunde
DDemocratic
P
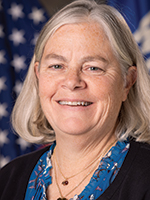
Tara Johnson
DDemocratic
P
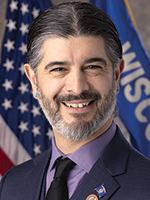
Vinnie Miresse
DDemocratic
Ask Maddy
·
AI policy assistant
Ask Maddy about AB 976
Scope: WI
Hi! I can help you understand AB 976. What would you like to know?
Try one of these
i
Maddy answers using official bill text and legislative records. Always verify before sharing.
Sources cited inline