

Income tax, state and corporate; tax credit for employers of National Guard members.
Summary
Individual and corporate income tax credit;employers of National Guard members and self-employed National Guardmembers. Provides for taxable years 2022 through 2026 a nonrefundabletax credit against individual and corporate income taxes for (i)wages paid by an employer to an employee who is a Virginia NationalGuard member or (ii) income of a self-employed Virginia National Guardmember attributable to his business. The bill provides that the amountof the credit is 25 percent if such member was in a military paystatus for 65 days or more during the taxable year or 15 percentif such member was in a military pay status for 45 to 64 days duringthe taxable year. The credit is not allowed if such member was ina military pay status for fewer than 45 days during the taxable year.
Bill status
in committee
1 of 4 stages cleared
Introduction
Jan 2022
Committee Review
Floor Vote
Governor
Introduced Jan 11, 2022
Last action Feb 7, 2022
Floor votes
How they voted
No floor votes recorded yet.
Full legislative history
Actions timeline
Total actions
6
Key actions
1
Committee
3
Feb 4, 2022
Lower · Passed
Subcommittee recommends continuing to 2023
lower
Feb 1, 2022
Committee
Assigned Finance sub: Subcommittee #3
lower
Jan 11, 2022
Committee
Referred to Committee on Finance
lower
Jan 11, 2022
Introduced
Prefiled and ordered printed; offered 01/12/22 22100092D
lower
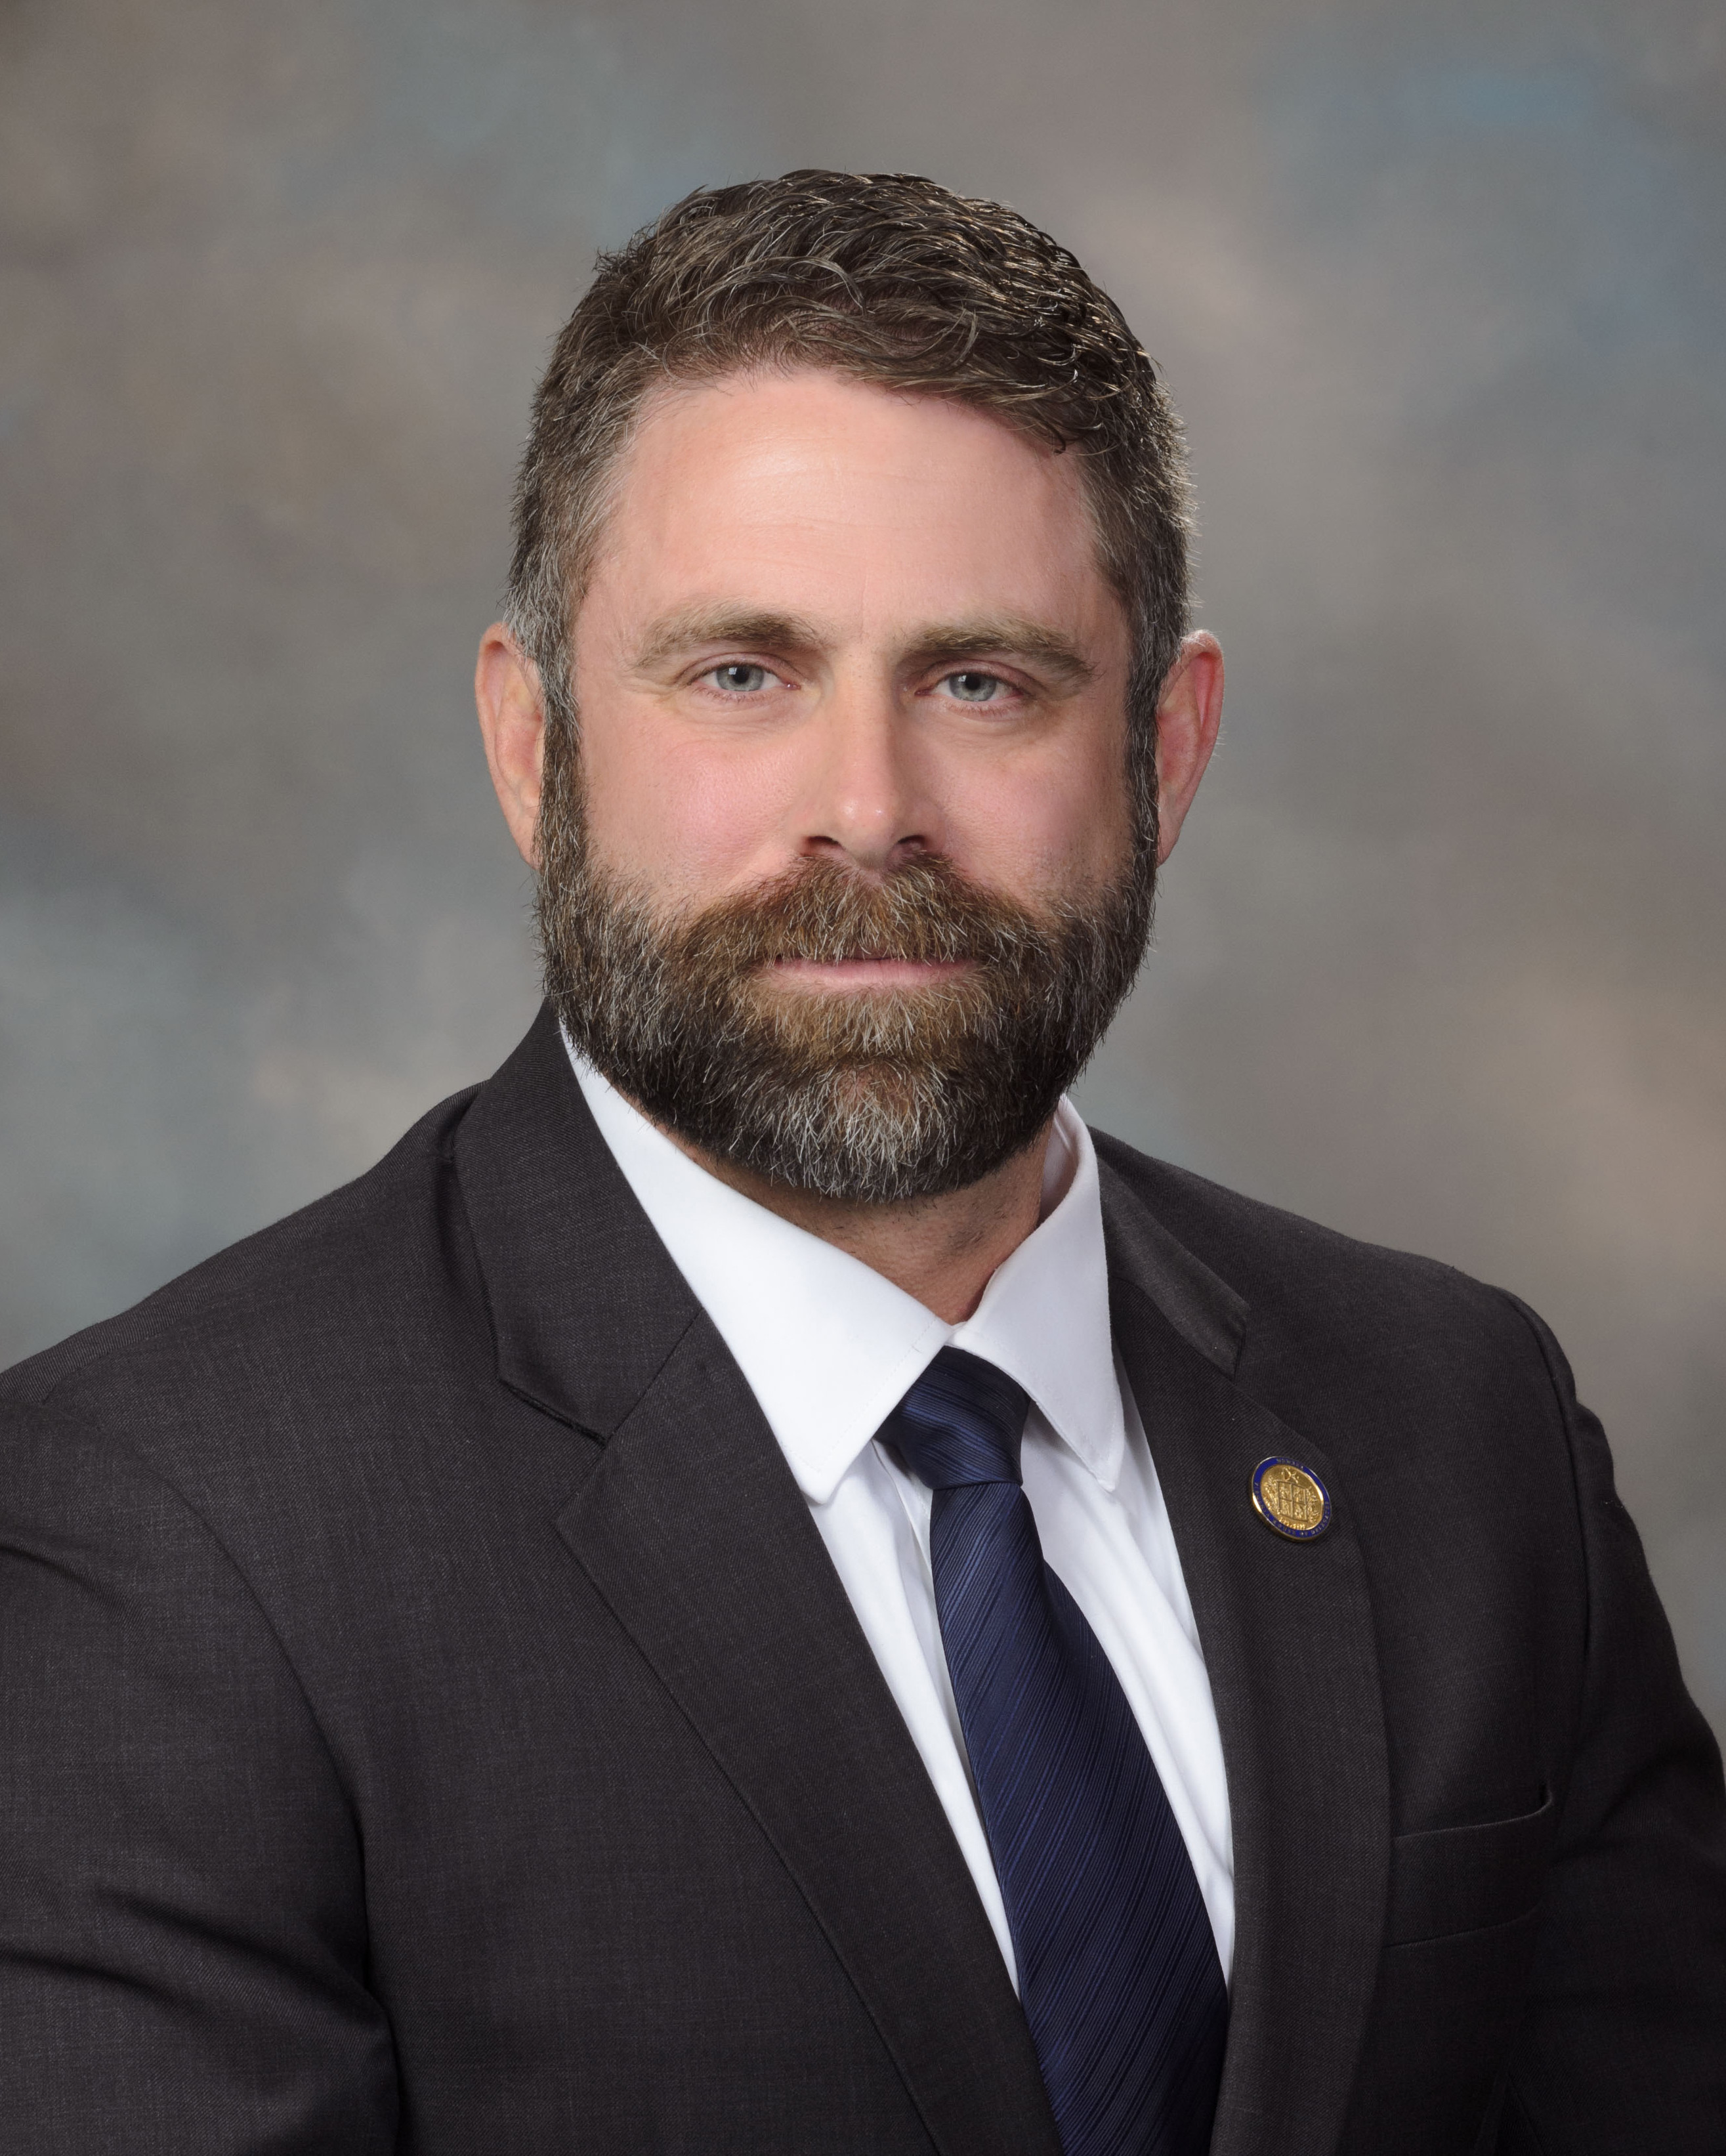
1 primary · 1 co-sponsor
Sponsors
Ask Maddy
·
AI policy assistant
Ask Maddy about HB 290
Scope: VA
Hi! I can help you understand HB 290. What would you like to know?
Try one of these
i
Maddy answers using official bill text and legislative records. Always verify before sharing.
Sources cited inline