

Consolidated corporate income tax; returns of affiliated corporations.
Summary
Consolidated corporate income tax returns ofaffiliated corporations. Simplifies the process by which companieselect to switch to consolidated corporate income tax return filingstatus and reduces from 20 to five years the period during which the affiliated group of corporations must have filed on the same basisprior to switching to consolidated return filing status. Currentlaw requires a group of corporations to apply to the Tax Commissionerfor permission to change the basis of the type of return filed andto meet some specific requirements in order for permission to begranted.
Bill status
in committee
1 of 4 stages cleared
Introduction
Jan 2020
Committee Review
Floor Vote
Governor
Introduced Jan 17, 2020
Last action Feb 5, 2020
Floor votes
How they voted
No floor votes recorded yet.
Full legislative history
Actions timeline
Total actions
6
Key actions
0
Committee
3
Jan 31, 2020
House of Delegates · Reported by committee
Subcommittee recommends continuing to 2021
Jan 29, 2020
House of Delegates · Referred to committee
Assigned Finance sub: Subcommittee #3
Jan 17, 2020
House of Delegates · Referred to committee
Referred to Committee on Finance
Jan 17, 2020
House of Delegates · Introduced
Presented and ordered printed 20105114D
1 primary · 0 co-sponsors
Sponsors
Role
Legislator
Party
State
District
P
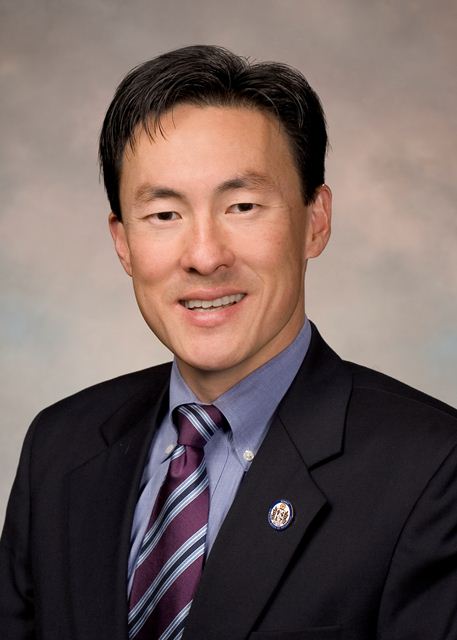
Mark L. Keam
DDemocratic
Ask Maddy
·
AI policy assistant
Ask Maddy about HB 1676
Scope: VA
Hi! I can help you understand HB 1676. What would you like to know?
Try one of these
i
Maddy answers using official bill text and legislative records. Always verify before sharing.
Sources cited inline