

Beginning Farmer Tax Incentive Act
The Beginning Farmer Tax Incentive Act (HR 6836) creates tax benefits for beginning farmers by excluding 40% of capital gains from selling qualifying farmland and up to $25,000 annually from lease income. Qualifying farmland must have been farmed by the seller’s family for at least 5 years. Beginning farmers are defined as new individuals with 1-10 years of farming experience (reported on Schedule F), those with beginner farm loans, or those with substantial farming knowledge. The policy directly supports new agricultural entrants through targeted tax relief, applying to land used for farming with specific ownership history requirements.
Bill status
in committee
1 of 4 stages cleared
Introduction
Dec 2025
Committee Review
Floor Vote
President
Introduced Dec 18, 2025
Last action Dec 18, 2025
Floor votes
How they voted
No floor votes recorded yet.
Full legislative history
Actions timeline
Total actions
2
Key actions
0
Committee
1
Dec 18, 2025
Committee
Referred to the House Committee on Ways and Means.
lower
Dec 18, 2025
Introduced
Introduced in House
lower
1 primary · 0 co-sponsors
Sponsors
Role
Legislator
Party
State
District
P
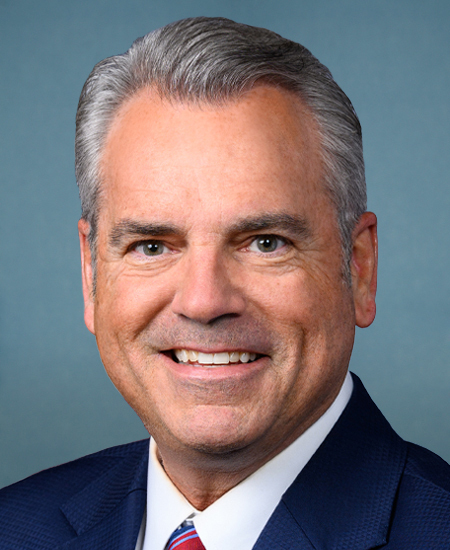
Mark Alford
RRepublican
Ask Maddy
·
AI policy assistant
Ask Maddy about HR 6836
Scope: US
Hi! I can help you understand HR 6836. What would you like to know?
Try one of these
i
Maddy answers using official bill text and legislative records. Always verify before sharing.
Sources cited inline