

Clarity in Lending Act
The Clarity in Lending Act creates a "safe harbor" for small-dollar credit products ($3,500 or less) that meet specific requirements, protecting covered entities (banks, credit unions, and their contractors) from civil penalties and private lawsuits. It requires repayment terms longer than 45 days, fully amortized payments, no rollovers, and prohibits prepayment penalties, overdraft fees, and nonsufficient funds fees. The bill also clarifies the definition of "abusive" acts for the Bureau of Consumer Financial Protection, mandates a 180-day cure period before enforcement actions, and limits look-back periods for penalties. This legislation directly affects small-dollar lenders and the Bureau's enforcement practices while maintaining consumer protections.
Bill status
in committee
1 of 4 stages cleared
Introduction
May 2024
Committee Review
Floor Vote
President
Introduced May 10, 2024
Last action Dec 3, 2024
Floor votes
How they voted
No floor votes recorded yet.
Full legislative history
Actions timeline
Total actions
6
Key actions
2
Committee
3
Amendments
1
Dec 3, 2024
Lower · Passed
Reported (Amended) by the Committee on Financial Services. H. Rept. 118-789.
lower
May 16, 2024
Introduced
Ordered to be Reported (Amended) by the Yeas and Nays: 27 - 22.
lower
May 16, 2024
Lower · Passed
Committee Consideration and Mark-up Session Held
lower
May 10, 2024
Committee
Referred to the House Committee on Financial Services.
lower
May 10, 2024
Introduced
Introduced in House
lower
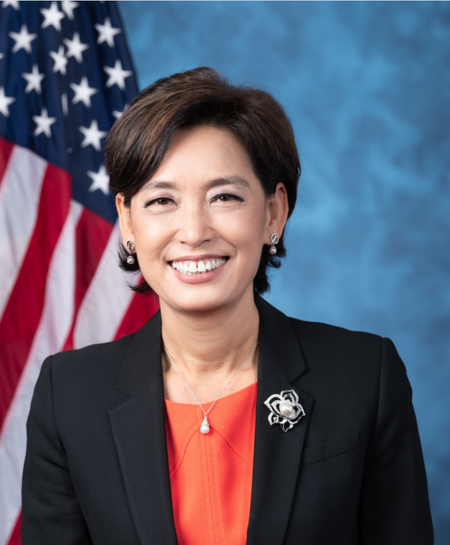
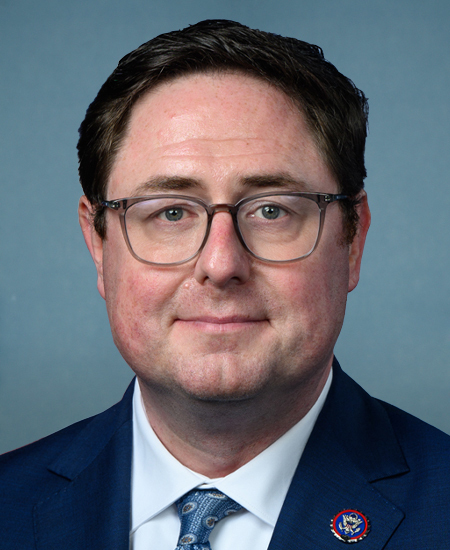
1 primary · 1 co-sponsor
Sponsors
Ask Maddy
·
AI policy assistant
Ask Maddy about HR 8338
Scope: US
Hi! I can help you understand HR 8338. What would you like to know?
Try one of these
i
Maddy answers using official bill text and legislative records. Always verify before sharing.
Sources cited inline