

To amend the Internal Revenue Code of 1986 to treat property transferred by gift or at death as sold for fair market value, and for other purposes.
Summary
This bill treats property transferred by gift or upon the death of a decedent as sold at its fair market value (thus requiring recognition of gain realized over the property's basis). Under current law there is a step up in basis of such property which allows for an exclusion of gain for gifts and estate property. The bill allows an exception to this fair market value rule for U.S. citizen spouses, charities, and certain tangible property. The bill allows a taxpayer an exclusion from income for up to $1 million (indexed for inflation) in gain resulting from transfers at death. The bill imposes certain information reporting requirements for gifts or bequests subject to this bill's fair market value rule. It also allows taxpayers to pay any tax due in two or more, but not more than seven, equal installments.
Bill status
in committee
1 of 4 stages cleared
Introduction
Mar 2021
Committee Review
Floor Vote
President
Introduced Mar 29, 2021
Last action Mar 29, 2021
Floor votes
How they voted
No floor votes recorded yet.
Full legislative history
Actions timeline
Total actions
2
Key actions
0
Committee
1
Mar 29, 2021
Committee
Referred to the House Committee on Ways and Means.
lower
Mar 29, 2021
Introduced
Introduced in House
lower
1 primary · 3 co-sponsors
Sponsors
Role
Legislator
Party
State
District
P
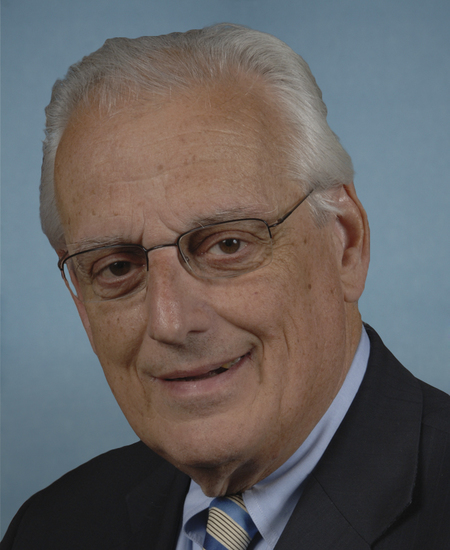
Bill Pascrell, Jr.
DDemocratic
Co
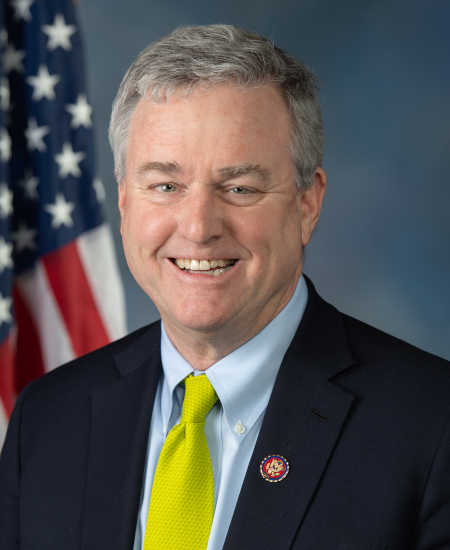
David J. Trone
DDemocratic
Co
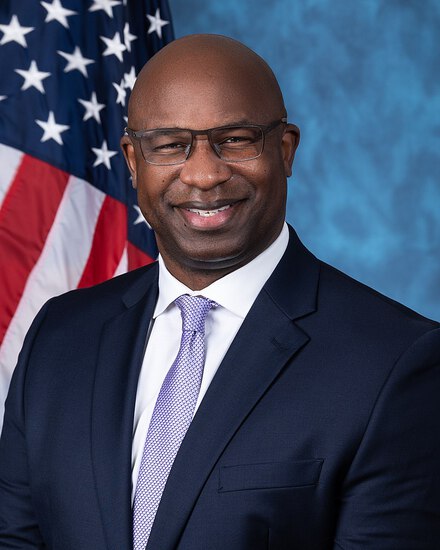
Jamaal Bowman
DDemocratic
Co
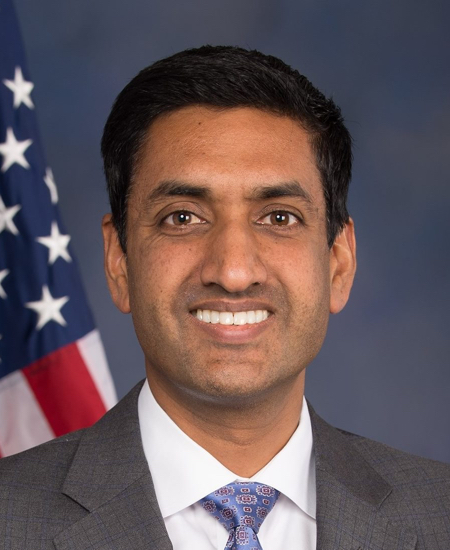
Ro Khanna
DDemocratic
Ask Maddy
·
AI policy assistant
Ask Maddy about HR 2286
Scope: US
Hi! I can help you understand HR 2286. What would you like to know?
Try one of these
i
Maddy answers using official bill text and legislative records. Always verify before sharing.
Sources cited inline