

Flat Tax Act
Summary
Flat Tax Act This bill authorizes an individual or a person engaged in business activity to make an irrevocable election to be subject to a flat tax (in lieu of the existing income tax provisions) of 19% for the first two years after an election is made, and 17% thereafter. The bill calculates taxable income for individual taxpayers by subtracting a basic standard deduction and an additional standard deduction for each dependent from the total of wages, retirement distributions, and unemployment compensation. "Business taxable income" is gross active income reduced by certain deductions for the cost of business inputs, wages, and retirement contributions. The bill imposes an employer tax on the value of excludable compensation provided to employees not engaged in business activity of 19% for the first two years after an election is made under this bill and 17% thereafter. The bill also repeals the estate, gift, and generation-skipping transfer taxes. A two-thirds vote of the House of Representatives and the Senate is required to increase the flat tax rate proposed by this bill or to reduce the amount of the standard deduction or business-related deductions allowed by this bill.
Bill status
in committee
1 of 4 stages cleared
Introduction
Feb 2021
Committee Review
Floor Vote
President
Introduced Feb 15, 2021
Last action Oct 1, 2021
Floor votes
How they voted
No floor votes recorded yet.
Full legislative history
Actions timeline
Total actions
3
Key actions
0
Committee
1
Feb 15, 2021
Committee
Referred to the Committee on Ways and Means, and in addition to the Committee on Rules, for a period to be subsequently determined by the Speaker, in each case for consideration of such provisions as fall within the jurisdiction of the committee concerned.
lower
Feb 15, 2021
Introduced
Introduced in House
lower
1 primary · 0 co-sponsors
Sponsors
Role
Legislator
Party
State
District
P
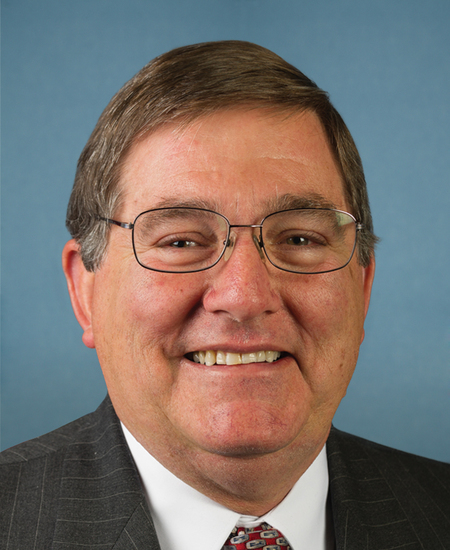
Michael C. Burgess
RRepublican
Ask Maddy
·
AI policy assistant
Ask Maddy about HR 1040
Scope: US
Hi! I can help you understand HR 1040. What would you like to know?
Try one of these
i
Maddy answers using official bill text and legislative records. Always verify before sharing.
Sources cited inline