

An Act amending the act of March 4, 1971 (P.L.6, No.2), known as the Tax Reform Code of 1971, in personal income tax, further providing for classes of income.
HB 217 amends Pennsylvania's tax code to require businesses to deduct start-up costs (like initial expenses for new ventures) entirely in the year incurred, rather than spreading deductions over multiple years as permitted under federal rules. This change affects new businesses and entrepreneurs with start-up expenses by altering how they calculate state personal income tax. The bill also allows business net losses to offset other income in the same tax year. These provisions apply to tax years beginning after December 31, 2025.
Bill status
in committee
1 of 4 stages cleared
Introduction
Jan 2025
Committee Review
Floor Vote
Governor
Introduced Jan 22, 2025
Last action Jan 22, 2025
Floor votes
How they voted
No floor votes recorded yet.
Full legislative history
Actions timeline
Total actions
1
Key actions
0
Committee
1
Jan 22, 2025
Committee
Referred to Finance
lower
1 primary · 21 co-sponsors
Sponsors
Role
Legislator
Party
State
District
P
Thomas Kutz
RRepublican
Co
Alec Ryncavage
RRepublican
Co
Andrew Kuzma
RRepublican
Co
Bryan Cutler
RRepublican
Co
Dallas Kephart
RRepublican
Co
Dave Zimmerman
RRepublican
Co
David Rowe
RRepublican
Co
Jim Struzzi
RRepublican
Co
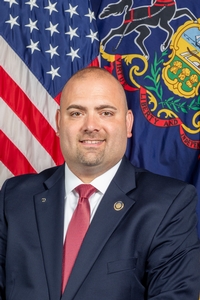
Joe Hamm
RRepublican
Co
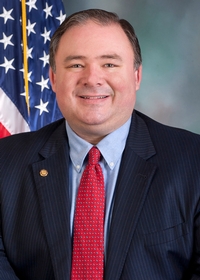
John Lawrence
RRepublican
Co
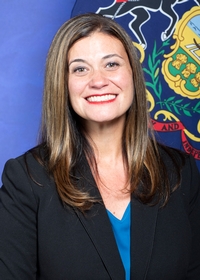
Kristin Marcell
RRepublican
Ask Maddy
·
AI policy assistant
Ask Maddy about HB 217
Scope: PA
Hi! I can help you understand HB 217. What would you like to know?
Try one of these
i
Maddy answers using official bill text and legislative records. Always verify before sharing.
Sources cited inline