

Provide for the recalculation of certain base-year employees under the Nebraska Advantage Act
Nebraska bill LB 954 amends the Nebraska Advantage Act to require the Department of Revenue to recalculate a business's base-year employee count if the business sells part of its operations covered under an Advantage Act agreement and the sold operations continue operating under a separate entity. The recalculation subtracts employees from the sold operations from the original count, but only if the sold operations remain active for at least 24 months and the sale wasn't primarily to close a location. Existing tax credits or incentives from before the sale remain unchanged. This applies to Advantage Act agreements entered into after December 31, 2016, directly affecting businesses participating in Nebraska's job creation and investment incentive program.
Bill status
signed
all 5 stages cleared
Introduction
Jan 2026
Committee Review
Feb 2026
Legislature Passage
Apr 2026
Legislature Passage
Mar 2026
Signed into Law
Apr 2026
Introduced Jan 12, 2026
Signed Apr 17, 2026
Maddy AI version diff · 1 comparison
What changed between versions
Introduced
→
Final Reading
·
5 edits
MODERATE
The bill was updated to include a 'Final Reading' status and revised the rules for recalculating tax credits when a business sells or transfers operations. The changes clarify that credits are recalculated if the sold business continues to operate under a new entity not part of the same tax group, while explicitly excluding sales made solely to close a location.
Scope change
The bill's scope was expanded to cover both sales and transfers of business operations, and it now specifically addresses scenarios where the business continues under a different legal entity.
ELIGIBILITY
The criteria for recalculating tax credits now explicitly include 'transfers' in addition to 'sales' of business operations.
The rule for when credits are recalculated was updated to apply when operations continue under an entity outside the original taxpayer's 'unitary group,' clarifying the legal threshold for the change.
The exemption for closing a location was updated to apply to both 'sales or transfers,' ensuring the exclusion covers all types of business dispositions.
TIMELINE
The effective date for the sale or transfer was changed from 'date of sale' to 'date of the sale or transfer' to align with the expanded scope.
TECHNICAL
The document header was updated to reflect the bill has reached the 'Final Reading' stage.
Floor votes · Legislature Mar 6, 2026
How they voted
35–0
Passed · 14 other
Total votes 49
Mar 6, 2026
N
Nonpartisan49
71% Yea
Vote distribution
All Yea
All Nay
Mixed
No data
Full legislative history
Actions timeline
Total actions
16
Key actions
5
Committee
2
Apr 17, 2026
Signed into law
Approved by Governor on April 14, 2026
executive
Apr 9, 2026
Legislature · Passed
President/Speaker signed
legislature
Apr 9, 2026
Legislature · Passed
Passed on Final Reading 44-3*-2
legislature
Mar 6, 2026
Legislature · Passed
von Gillern AM2209 adopted
legislature
Feb 6, 2026
Legislature · Passed
Placed on General File
legislature
Jan 14, 2026
Committee
Referred to Revenue Committee
legislature
Jan 12, 2026
Introduced
Date of introduction
legislature
1 primary · 0 co-sponsors
Sponsors
Role
Legislator
Party
State
District
P
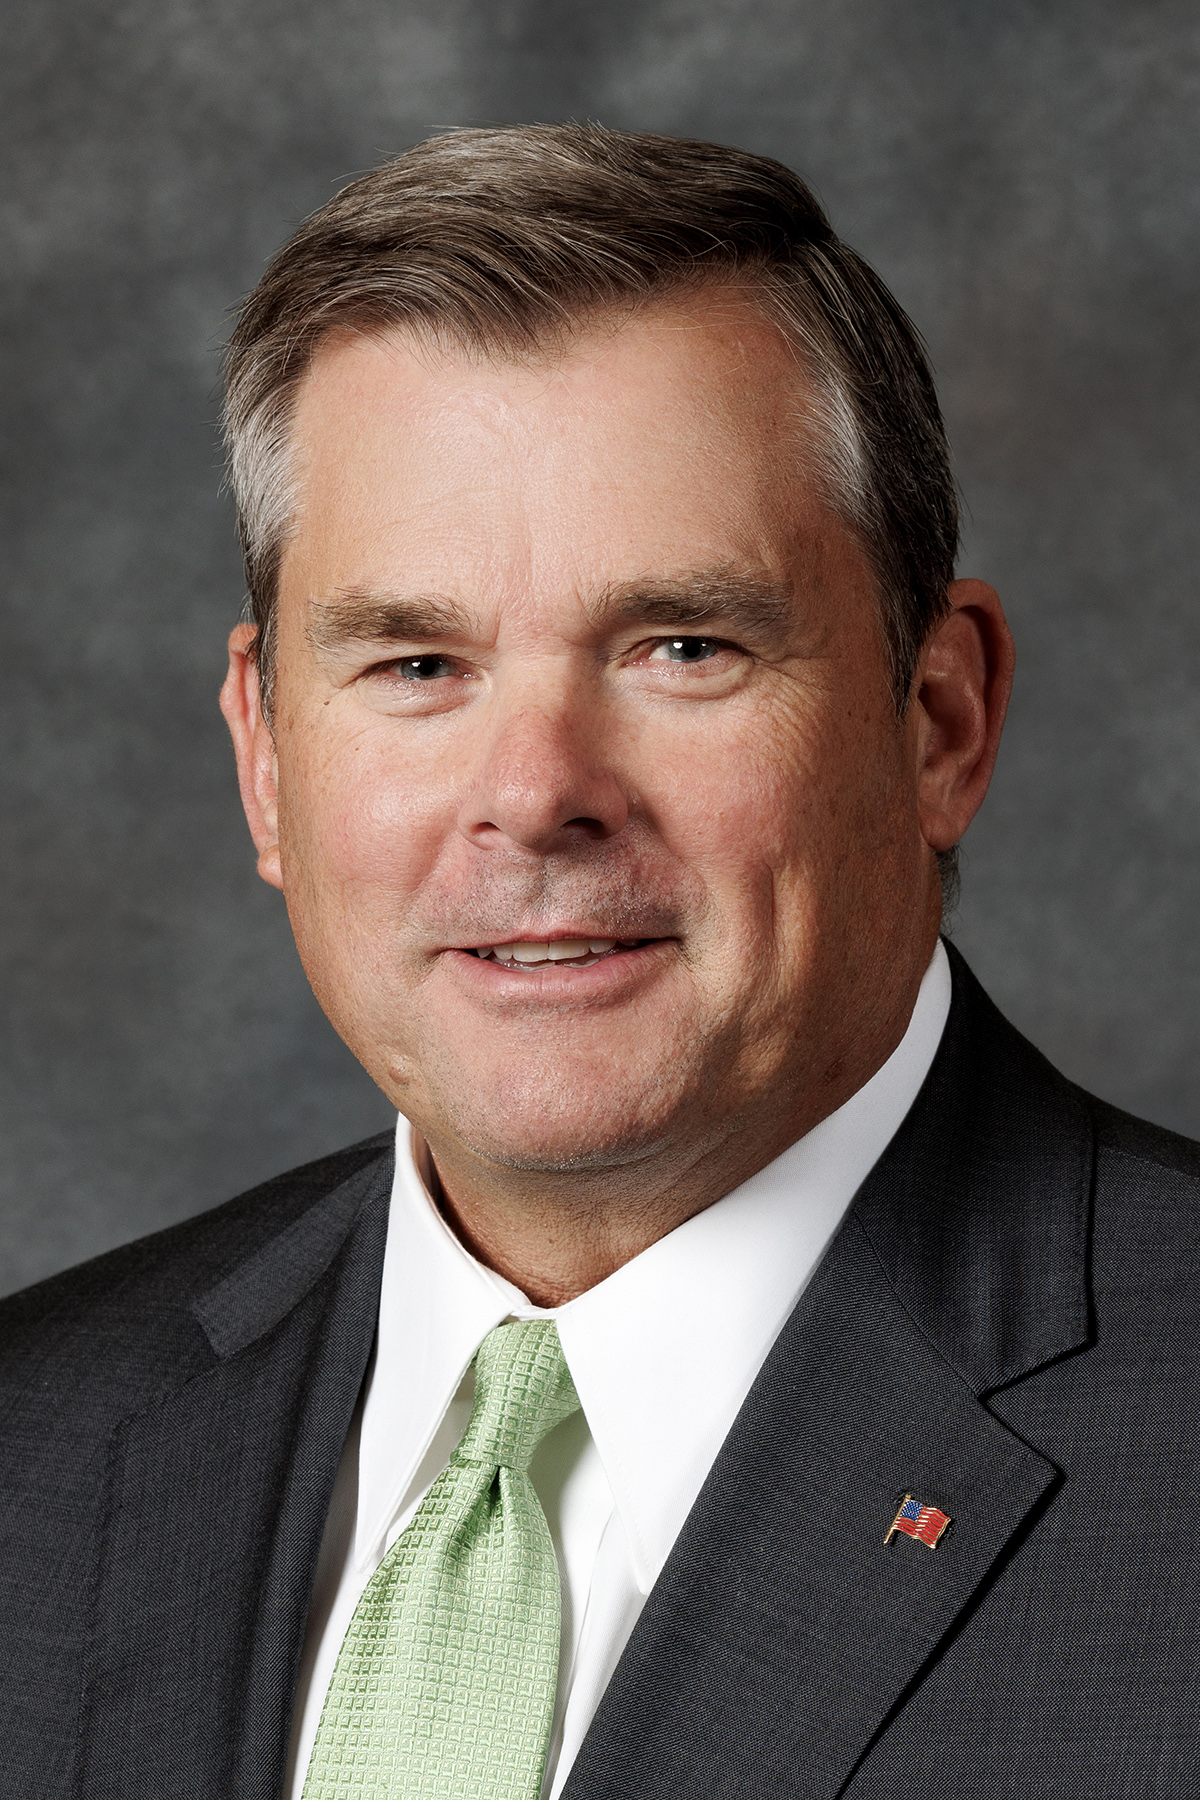
Brad von Gillern
NNonpartisan
Ask Maddy
·
AI policy assistant
Ask Maddy about LB 954
Scope: NE
Hi! I can help you understand LB 954. What would you like to know?
Try one of these
i
Maddy answers using official bill text and legislative records. Always verify before sharing.
Sources cited inline