

Revise laws to reduce property taxes while preserving the current 95 school equalization mills
HB 483 aims to reduce property taxes by revising school funding laws, while preserving the existing 95 school equalization mills. The bill fixes state and county school equalization mills and vocational-technical education mills, and exempts school levies from general property tax increase limits. It also increases guaranteed tax base multipliers for fiscal year 2026 and raises state reimbursement rates for school transportation, which helps lower local property tax burdens. Additionally, the bill requires reports from the Office of Public Instruction and Department of Revenue on the impacts of property reappraisal on school funding and property taxes.
Bill status
signed
all 5 stages cleared
Introduction
Feb 2025
Committee Review
Apr 2025
House Passage
May 2025
Senate Passage
May 2025
Signed into Law
May 2025
Introduced Feb 12, 2025
Signed May 16, 2025
Maddy AI version diff · 7 comparisons
What changed between versions
HB0483_X(15).pdf
→
HB0483_X(16).pdf
·
2 edits
MINOR
The bill modifies the formula used to calculate the maximum property tax levy for governmental entities, shifting the calculation from the prior year's assessed tax amount to the current year's actually assessed tax amount. It also updates the rules for reporting tax increment financing (TIF) values when a district terminates, ensuring they are reported in the correct year based on certification timing rather than termination timing. These changes aim to align levy calculations more closely with current property assessments and clarify reporting timelines for TIF districts.
Scope change
The scope of the levy calculation formula has been adjusted to reflect current year assessments instead of prior year assessments, and the applicability of TIF reporting rules has been refined based on certification dates.
REQUIREMENT
The formula for determining the maximum number of mills a governmental entity can impose now uses the amount of property tax actually assessed in the current year, rather than the amount assessed in the prior year.
Reporting of tax increment financing values for terminated districts is now based on when taxable values are certified, ensuring the value is reported in the year of certification rather than the year of termination.
Floor votes · Senate Apr 22, 2025 · House Apr 5, 2025
How they voted
46–4
Passed
Total votes 50
Apr 22, 2025
D
Democratic18
100% Yea
R
Republican32
87% Yea
Vote distribution
All Yea
All Nay
Mixed
No data
Full legislative history
Actions timeline
Total actions
51
Key actions
11
Committee
9
May 13, 2025
Signed into law
(H) Signed by Governor
lower
May 2, 2025
Upper · Passed
(S) Signed by President
upper
May 1, 2025
Lower · Passed
(H) Signed by Speaker
lower
Apr 22, 2025
Senate · Passed
Senate Vote: pass (46-4)
senate
Apr 16, 2025
Upper · Passed
(S) Committee Report - (S) Taxation
upper
Apr 16, 2025
Upper · Passed
(S) Committee Executive Action - (S) Taxation
upper
Apr 7, 2025
Committee
(S) Referred to Committee - (S) Taxation
upper
Apr 5, 2025
House · Passed
House Vote: pass (87-11-2)
house
Mar 31, 2025
Lower · Passed
(H) Committee Report - (H) Appropriations
lower
Mar 31, 2025
Lower · Passed
(H) Committee Executive Action - (H) Appropriations
lower
Mar 1, 2025
Committee
(H) Rereferred to Committee - (H) Appropriations
lower
Feb 28, 2025
Lower · Passed
(H) Committee Report - (H) Taxation
lower
Feb 28, 2025
Lower · Passed
(H) Committee Executive Action - (H) Taxation
lower
Feb 13, 2025
Committee
(H) Referred to Committee - (H) Taxation
lower
Feb 12, 2025
Introduced
(H) Introduced
lower
1 primary · 0 co-sponsors
Sponsors
Role
Legislator
Party
State
District
P
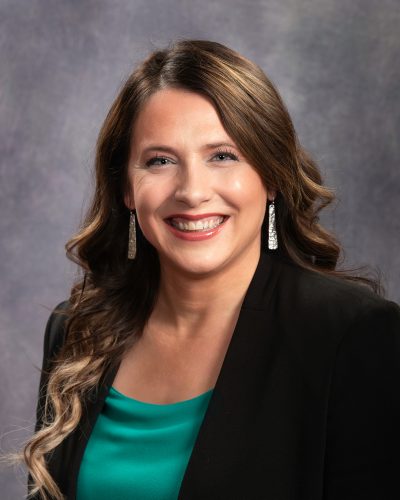
Courtenay Sprunger
RRepublican
Ask Maddy
·
AI policy assistant
Ask Maddy about HB 483
Scope: MT
Hi! I can help you understand HB 483. What would you like to know?
Try one of these
i
Maddy answers using official bill text and legislative records. Always verify before sharing.
Sources cited inline