

Eliminate reference to personal property farm manual for property tax purposes
HB 108 eliminates a requirement for Montana's Department of Revenue to create a supplemental valuation manual when agricultural implements and machinery (like farm equipment) aren't listed in national appraisal guides. This change directly affects farmers and ranchers who own such equipment, as their property tax valuations will now rely solely on existing national guides instead of needing a separate state manual. The bill amends property tax law to remove the specific provision requiring the supplemental manual, streamlining the valuation process for the Department of Revenue. The change takes effect for tax years beginning after December 31, 2025.
Bill status
signed
all 5 stages cleared
Introduction
Dec 2024
Committee Review
Mar 2025
House Passage
Mar 2025
Senate Passage
Mar 2025
Signed into Law
Apr 2025
Introduced Dec 20, 2024
Signed Apr 7, 2025
Maddy AI version diff · 4 comparisons
What changed between versions
HB0108_1(9).pdf
→
HB0108_X.pdf
·
3 edits
MINOR
This bill simplifies property tax valuation rules for agricultural equipment by removing the requirement for the Department of Revenue to create a supplemental manual for items not listed in official guides. Instead, the law now states that the market value is simply the average wholesale value shown in national guides, or the value before reconditioning and profit margin if the item is not listed. The bill also updates formatting and numbering conventions throughout the statute.
Scope change
The scope of valuation rules for agricultural implements and machinery was narrowed by eliminating the administrative burden of creating supplemental valuations for unlisted items, relying solely on existing national guides or wholesale values.
REQUIREMENT
Eliminated the mandate for the Department of Revenue to prepare a supplemental valuation manual for agricultural implements and machinery that are not found in official national guides.
DEFINITION
Changed the valuation method for unlisted agricultural equipment to use the 'value before reconditioning and profit margin' instead of requiring a specific supplemental manual calculation.
TECHNICAL
Updated the bill header and title to reflect the new streamlined language and corrected section numbering inconsistencies.
Floor votes · Senate Mar 26, 2025 · House Jan 22, 2025
How they voted
50–0
Passed
Total votes 50
Mar 26, 2025
D
Democratic18
100% Yea
R
Republican32
100% Yea
Vote distribution
All Yea
All Nay
Mixed
No data
Full legislative history
Actions timeline
Total actions
37
Key actions
9
Committee
6
Apr 7, 2025
Signed into law
(H) Signed by Governor
lower
Mar 31, 2025
Upper · Passed
(S) Signed by President
upper
Mar 28, 2025
Lower · Passed
(H) Signed by Speaker
lower
Mar 26, 2025
Senate · Passed
Senate Vote: pass (50-0)
senate
Mar 20, 2025
Upper · Passed
(S) Committee Report - (S) Taxation
upper
Mar 19, 2025
Upper · Passed
(S) Committee Executive Action - (S) Taxation
upper
Feb 18, 2025
Committee
(S) Referred to Committee - (S) Taxation
upper
Jan 22, 2025
House · Passed
House Vote: pass (100-0)
house
Jan 14, 2025
Lower · Passed
(H) Committee Report - (H) Taxation
lower
Jan 14, 2025
Lower · Passed
(H) Committee Executive Action - (H) Taxation
lower
Dec 23, 2024
Committee
(H) Referred to Committee - (H) Taxation
lower
Dec 20, 2024
Introduced
(H) Introduced
lower
1 primary · 0 co-sponsors
Sponsors
Role
Legislator
Party
State
District
P
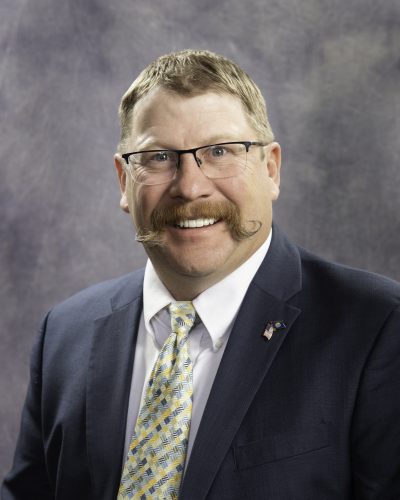
Eric Tilleman
RRepublican
Ask Maddy
·
AI policy assistant
Ask Maddy about HB 108
Scope: MT
Hi! I can help you understand HB 108. What would you like to know?
Try one of these
i
Maddy answers using official bill text and legislative records. Always verify before sharing.
Sources cited inline