HB 1427 Mississippi House · 2025 Regular Session

Mississippi Credit Availability Act; extend repealer and revise and create cap adjustment based on the CPI-U.

HB 1427, the Mississippi Credit Availability Act, increases the maximum balance for credit availability accounts from $2,500 to $3,250 and requires annual adjustments based on the Consumer Price Index for Urban Consumers (CPI-U). This affects small lenders (licensees) and their customers who use short-term, fully amortized loans (4-12 months) with monthly payments. The bill mandates the Department of Banking and Consumer Finance to adjust the limit yearly by applying the prior year’s CPI-U to the previous maximum, rounding up to the nearest $10. The bill died in committee on March 4, 2025, and did not become law.
Bill status died 3 of 5 stages cleared
Introduction
Feb 2025
Committee Review
Feb 2025
House Passage
Feb 2025
Senate Passage
Governor
Introduced Feb 12, 2025 Last action Mar 4, 2025
Maddy AI version diff · 1 comparison

What changed between versions

As Introduced → Current version · 9 edits
MAJOR
This bill reenacts and updates Mississippi's Credit Availability Act, primarily increasing the maximum loan balance from $2,500 to $3,250 and establishing an automatic annual adjustment mechanism tied to the Consumer Price Index. It also clarifies licensing requirements, fee structures, and enforcement procedures for credit availability licensees.
Scope change
The bill maintains the same scope of applying to credit availability licensees but expands the maximum loan amount and adds an automatic inflation adjustment mechanism.
REQUIREMENT

Increased maximum outstanding principal balance from $2,500 to $3,250 for credit availability accounts.

Established automatic annual adjustment of the maximum loan balance using the Consumer Price Index, rounded up to the nearest $10 increment.

Updated license fee structure with initial fee of $750 and annual renewal fee of $475, plus late penalties.

Added fingerprint requirements for background checks on owners and executives of licensed businesses.

Adjusted handling fee and origination fee structures based on transaction amounts, with different terms for loans under $500 versus over $500.

TIMELINE

Extended the repeal date for reenacted sections from July 1, 2022 to July 1, 2030.

Set effective date of the act as July 1, 2025.

DEFINITION

Added new definitions for 'Appropriate law enforcement agency' and 'Attorney General' to clarify enforcement roles.

ENFORCEMENT

Added provisions for civil penalties up to $500 per violation and forfeiture of bonds upon conviction.

Floor votes · House Feb 11, 2025

How they voted

110–0
Passed · 9 other
Total votes 119
Feb 11, 2025
D Democratic39
39 Yea
100% Yea
I Independent2
1 Yea 1
50% Yea
R Republican78
70 Yea 8
89% Yea
Vote distribution
All Yea All Nay Mixed No data
Full legislative history

Actions timeline

Total actions
6
Key actions
2
Committee
3
Feb 17, 2025
Committee
Referred To Business and Financial Institutions
upper
Feb 12, 2025
Introduced
Transmitted To Senate
lower
Feb 11, 2025
Lower · Passed
Passed
lower
Jan 28, 2025
Lower · Passed
Title Suff Do Pass
lower
Jan 20, 2025
Committee
Referred To Banking and Financial Services
lower
1 primary · 0 co-sponsors

Sponsors

Role
Legislator
Party
State
District
P
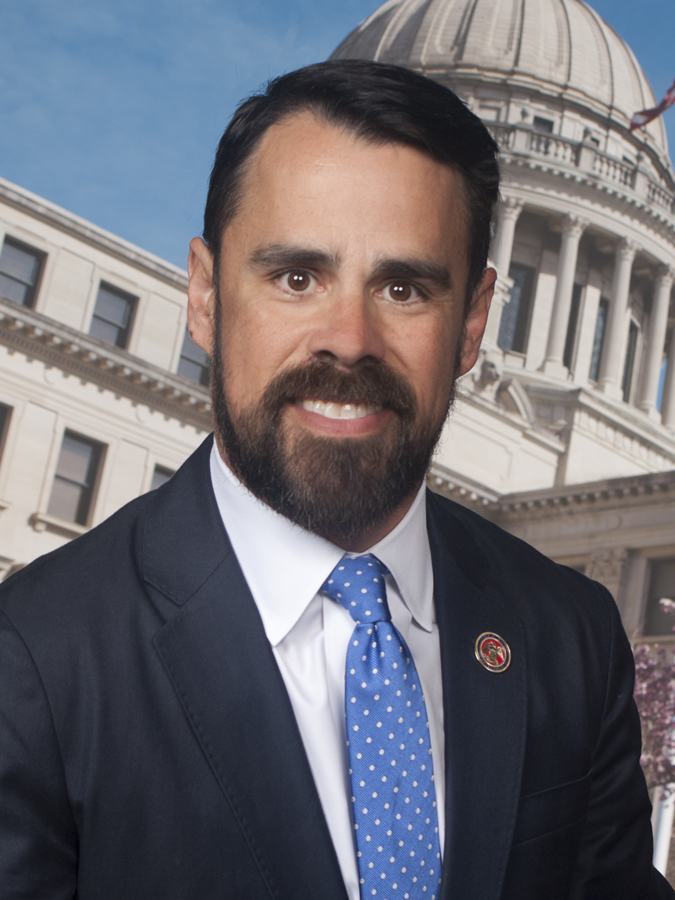
Photo of Shane Aguirre
Shane Aguirre
RRepublican
MS
17