

Financial Institutions - Licensing of Affiliated Insurance Producer-Mortgage Loan Originators - Alterations
HB 38 creates a new licensing pathway for mortgage loan originators affiliated with insurance producers who work exclusively for a single financial institution or mortgage lender. It requires the Commissioner of Financial Regulation to approve eligible entities - based on regulatory standing and compliance with laws - allowing them to originate mortgages under this specific category. The bill restricts these originators to working only for their sponsoring institution, prohibits handling borrower funds, and mandates that the sponsoring institution supervise them and share liability for their activities. This affects mortgage lenders and financial institutions seeking streamlined licensing while maintaining consumer safeguards.
Bill status
signed
all 5 stages cleared
Introduction
Oct 2025
Committee Review
Apr 2026
House of Delegates Passage
Apr 2026
Senate Passage
Apr 2026
Signed into Law
May 2026
Introduced Oct 28, 2025
Signed May 12, 2026
Maddy AI version diff · 1 comparison
What changed between versions
First - Financial Institutions - Licensing of Affiliated Insurance Producer-Mortgage Loan Originators - Alteration
→
Third - Financial Institutions - Licensing of Affiliated Insurance Producer-Mortgage Loan Originators - Alterations
·
3 edits
MINOR
The bill was amended to clarify that the licensing requirements apply to both financial institutions and mortgage lenders, removing previous ambiguity about whether mortgage lenders could be sponsors. The changes also update the text to ensure consistency in terminology and formatting throughout the statute.
Scope change
The bill's scope was expanded to explicitly include mortgage lenders as eligible sponsors alongside financial institutions, whereas the original text was less clear on this point.
ELIGIBILITY
Updated the definition of eligible sponsors to explicitly include both financial institutions and mortgage lenders, ensuring both can sponsor affiliated producers.
REQUIREMENT
Revised the criteria for Commissioner approval to align with the expanded eligibility, ensuring mortgage lenders meet the same standards as financial institutions.
TECHNICAL
Corrected formatting inconsistencies and repetitive language throughout the bill to improve readability and legal clarity.
Floor votes · Senate Mar 25, 2026 · House of Delegates Feb 20, 2026
How they voted
46–0
Passed · 3 other
Total votes 49
Mar 25, 2026
D
Democratic36
94% Yea
R
Republican13
92% Yea
Vote distribution
All Yea
All Nay
Mixed
No data
Full legislative history
Actions timeline
Total actions
19
Key actions
10
Committee
6
May 12, 2026
Signed into law
Approved by the Governor - Chapter 512
executive
Apr 13, 2026
Lower · Passed
Returned Passed
lower
Apr 13, 2026
Upper · Passed
Third Reading Passed
upper
Apr 9, 2026
Upper · Passed
Favorable Adopted
upper
Apr 9, 2026
Upper · Passed
Favorable Report by Finance
upper
Mar 25, 2026
Senate · Passed
Senate Vote: pass (46-0-3)
senate
Feb 27, 2026
Committee
Referred Finance
upper
Feb 26, 2026
Lower · Passed
Third Reading Passed
lower
Feb 25, 2026
Lower · Passed
Favorable with Amendments {
lower
Feb 24, 2026
Lower · Passed
Favorable with Amendments Report by Economic Matters
lower
Feb 20, 2026
House Of Delegates · Passed
House of Delegates Vote: pass (137-0-5)
house of delegates
Jan 14, 2026
Committee
First Reading Economic Matters
lower
Oct 28, 2025
Introduced
Pre-filed
lower
1 primary · 0 co-sponsors
Sponsors
Role
Legislator
Party
State
District
P
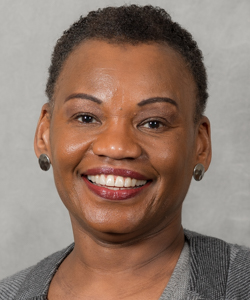
Pam Queen
DDemocratic
Ask Maddy
·
AI policy assistant
Ask Maddy about HB 38
Scope: MD
Hi! I can help you understand HB 38. What would you like to know?
Try one of these
i
Maddy answers using official bill text and legislative records. Always verify before sharing.
Sources cited inline