

TAX RETURN: Modifies statutory timelines, penalty calculations, and exceptions for penalties for the payment of certain estimated taxes (EN DECREASE GF RV See Note)
HB 633 modifies Louisiana's estimated income tax rules for individuals and corporations, primarily affecting taxpayers who make quarterly estimated payments. It introduces a new safe harbor to avoid penalties: if taxpayers pay at least 80% of their annualized tax (based on income earned in the first 3-11 months of the year), they won’t face penalties for underpayment. The bill also adjusts timelines for penalty calculations, extends deadlines for applying to adjust overpayments, and repeals an outdated penalty exception. These changes apply to tax years beginning January 1, 2026.
Bill status
signed
all 5 stages cleared
Introduction
Feb 2026
Committee Review
Apr 2026
House Passage
May 2026
Senate Passage
Apr 2026
Signed into Law
May 2026
Introduced Feb 27, 2026
Signed May 22, 2026
Maddy AI version diff · 4 comparisons
What changed between versions
HB633 Original
→
HB633 Act 307
·
4 edits
MODERATE
This bill updates Louisiana's tax laws to clarify how penalties for unpaid estimated income taxes are calculated. It modifies the percentage thresholds used to determine if a taxpayer has paid enough to avoid penalties and changes the specific dates used to measure the period of underpayment. The act also repeals a section regarding excessive tax adjustments and clarifies rules for farmers and fishermen.
Scope change
The bill expands the scope of the penalty calculation rules to include specific provisions for individuals with income from farming and fishing, adjusting the percentage thresholds from 70% to 66.67% for these groups.
REQUIREMENT
Changed the percentage threshold for avoiding estimated tax penalties from 70% to 66.67% (two-thirds) for individuals whose income comes from farming or fishing.
Repealed the specific section (R.S. 47:118(D)(1)(c)) that previously defined how to calculate the period of underpayment under certain conditions.
TIMELINE
Updated the statutory language to change the deadline for the underpayment period from the 15th day of the fourth month to the 15th day of the fifth month following the close of the taxable year.
DEFINITION
Refined the definition of 'required annual payment' to explicitly include the tax from the preceding year as a benchmark for calculating the required installment amount.
Floor votes · Senate Apr 29, 2026 · House Mar 23, 2026
How they voted
33–0
Passed · 7 other
Total votes 40
Apr 29, 2026
D
Democratic12
66% Yea
R
Republican28
89% Yea
Vote distribution
All Yea
All Nay
Mixed
No data
Full legislative history
Actions timeline
Total actions
26
Key actions
5
Committee
5
May 13, 2026
Lower · Passed
Read by title, roll called, yeas 99, nays 0, Senate amendments concurred in.
lower
Apr 29, 2026
Upper · Passed
Rules suspended. Senate floor amendments read and adopted. Read by title, passed by a vote of 31 yeas and 0 nays, and ordered returned to the House. Motion to reconsider tabled.
upper
Apr 21, 2026
Committee
Read by title and referred to the Legislative Bureau.
upper
Apr 20, 2026
Upper · Passed
Reported favorably.
upper
Mar 23, 2026
Lower · Passed
Read third time by title, amended, roll called on final passage, yeas 100, nays 0. Finally passed, title adopted, ordered to the Senate.
lower
Mar 16, 2026
Lower · Passed
Reported with amendments (14-0).
lower
Mar 9, 2026
Committee
Read by title, under the rules, referred to the Committee on Ways and Means.
lower
Feb 27, 2026
Committee
Under the rules, provisionally referred to the Committee on Ways and Means.
lower
1 primary · 0 co-sponsors
Sponsors
Role
Legislator
Party
State
District
P
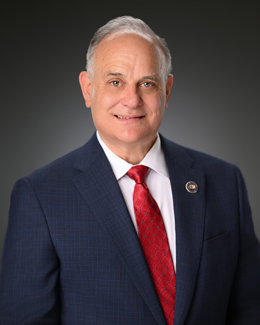
Tony Bacala
RRepublican
Ask Maddy
·
AI policy assistant
Ask Maddy about HB 633
Scope: LA
Hi! I can help you understand HB 633. What would you like to know?
Try one of these
i
Maddy answers using official bill text and legislative records. Always verify before sharing.
Sources cited inline