

TAX/TAXATION: Provides for the treatment of certain pass through entities under the inventory tax credit. (gov sig) (EN INCREASE SD RV See Note)
SB 65 extends the carry-forward period for inventory tax credits from five to ten years for pass-through business entities (like partnerships and S-corporations). This change directly affects businesses that use the inventory tax credit but cannot fully utilize it in a single year. The key provision modifies how unused credits can be applied, allowing these businesses to carry forward credits for a longer period instead of losing them after five years. The bill makes a technical adjustment to existing tax law without creating new taxes or changing credit rates.
Bill status
signed
all 5 stages cleared
Introduction
Apr 2025
Committee Review
May 2025
Senate Passage
Jun 2025
House Passage
May 2025
Signed into Law
Jun 2025
Introduced Apr 2, 2025
Signed Jun 20, 2025
Maddy AI version diff · 4 comparisons
What changed between versions
SB65 Original
→
SB65 Act 412
·
4 edits
MODERATE
This bill updates the Louisiana inventory tax credit to explicitly exclude C-corporations, estates, and trusts from claiming the credit for tax periods starting on or after July 1, 2026. It introduces special rules allowing cooperatives and S-corporations to claim the credit if benefits flow directly to their members or shareholders. Additionally, the carry-forward period for unused credits is extended from five to ten years for credits expiring after January 1, 2025.
Scope change
The bill expands the scope of the credit to include cooperatives and S-corporations under specific conditions, while simultaneously narrowing eligibility by permanently excluding C-corporations, estates, and trusts for future tax periods.
ELIGIBILITY
C-corporations, estates, and trusts are now explicitly prohibited from claiming the inventory tax credit for taxable periods beginning on or after July 1, 2026.
Cooperatives are now allowed to claim the credit if they distribute patronage dividends to members, and S-corporations can claim the credit only for amounts that flow through to shareholders.
TIMELINE
The carry-forward period for unused tax credits is extended from five years to ten years for credits that would have expired on or after January 1, 2025.
REQUIREMENT
Credits for C-corporations that exceed their tax liability are no longer refundable and can only be carried forward.
Floor votes · Senate May 7, 2025 · House May 28, 2025
How they voted
34–0
Passed · 3 other
Total votes 37
May 7, 2025
D
Democratic11
81% Yea
R
Republican26
96% Yea
Vote distribution
All Yea
All Nay
Mixed
No data
Full legislative history
Actions timeline
Total actions
23
Key actions
5
Committee
4
Amendments
1
Jun 11, 2025
Upper · Passed
Amendments proposed by the House read and concurred in by a vote of 34 yeas and 0 nays.
upper
May 28, 2025
Lower · Passed
Read third time by title, amended, roll called on final passage, yeas 95, nays 0. Finally passed, ordered to the Senate.
lower
May 20, 2025
Introduced
Reported without Legislative Bureau amendments.
lower
May 19, 2025
Lower · Passed
Reported favorably (11-0). Referred to the Legislative Bureau.
lower
May 12, 2025
Committee
Read by title, under the rules, referred to the Committee on Ways and Means.
lower
May 7, 2025
Upper · Passed
Senate floor amendments read and adopted. Read by title and passed by a vote of 36 yeas and 0 nays; ordered reengrossed and sent to the House. Motion to reconsider tabled.
upper
Apr 15, 2025
Upper · Passed
Reported with amendments.
upper
Apr 14, 2025
Committee
Introduced in the Senate; read by title. Rules suspended. Read second time and referred to the Committee on Revenue and Fiscal Affairs.
upper
1 primary · 0 co-sponsors
Sponsors
Role
Legislator
Party
State
District
P
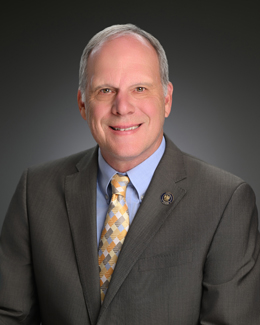
Franklin Foil
RRepublican
Ask Maddy
·
AI policy assistant
Ask Maddy about SB 65
Scope: LA
Hi! I can help you understand SB 65. What would you like to know?
Try one of these
i
Maddy answers using official bill text and legislative records. Always verify before sharing.
Sources cited inline