

Reporting Adjustments To Taxable Income
Summary
The act changes how pass-through entities may elect to pay taxes, specifies how to report and account for adjustments to federal taxable income, and changes the due date for filing a C-corporation income tax return. Partnerships and S corporations (pass-through entities) have had 3 options for ensuring that the income taxes owed by nonresident owners will be paid. Pass-through entities have been able to file a composite return on behalf of these owners, withhold an estimated tax payment, or collect and file an agreement that the owner will file a separate return. For income tax years beginning on and after January 1, 2024, section 1 of the act consolidates the composite return and withholding options and clarifies the calculation of the required payment. Section 2 adopts the multistate tax commission's model statute for reporting adjustments to federal taxable income. When federal taxable income is adjusted by the internal revenue service, or by the taxpayer through an amended federal return, the taxpayer must also report that change to the state. Those changes have had to be reported within 30 days and new federal centralized partnership audit procedures have not been addressed. The act provides additional time for reporting adjustments and allows pass-through entities to handle adjustments at the entity level on behalf of their owners. Section 3 changes the due date for income tax returns by C corporations. State income tax returns have had to be filed by C corporations by April 15, and prior to 2017, the federal income tax return deadline for C corporations was March 15. This meant that the state's April 15 due date and October 15 extension deadline was one month after the federal due date. In 2017, congress moved the federal due date for C corporations to April 15. Section 3 restores the one-month lag by changing the state due date to May 15, with a November 15 extension deadline. APPROVED by Governor June 1, 2023 PORTIONS EFFECTIVE January 1, 2024 PORTIONS EFFECTIVE August 7, 2023 NOTE: This act was passed without a safety clause and portions of it take effect 90 days after sine die. (Note: This summary applies to this bill as enacted.)
Bill status
signed
all 5 stages cleared
Introduction
Mar 2023
Committee Review
May 2023
House Passage
Apr 2023
Senate Passage
May 2023
Signed into Law
Jun 2023
Introduced Mar 30, 2023
Signed Jun 1, 2023
Floor votes · Senate May 6, 2023 · House Apr 24, 2023
How they voted
29–0
Passed · 1 other
Total votes 30
May 6, 2023
D
Democratic21
95% Yea
R
Republican9
100% Yea
Vote distribution
All Yea
All Nay
Mixed
No data
Full legislative history
Actions timeline
Total actions
15
Key actions
5
Committee
4
Jun 1, 2023
Signed into law
Governor Signed
executive
May 6, 2023
Upper · Passed
Senate Third Reading Passed - No Amendments
upper
May 5, 2023
Upper · Passed
Senate Committee on Appropriations Refer Unamended to Senate Committee of the Whole
upper
May 2, 2023
Committee
Senate Committee on Finance Refer Unamended to Appropriations
upper
Apr 25, 2023
Introduced
Introduced In Senate - Assigned to Finance
upper
Apr 24, 2023
Lower · Passed
House Third Reading Passed - No Amendments
lower
Apr 18, 2023
Lower · Passed
House Committee on Appropriations Refer Unamended to House Committee of the Whole
lower
Apr 10, 2023
Committee
House Committee on Finance Refer Unamended to Appropriations
lower
Mar 30, 2023
Introduced
Introduced In House - Assigned to Finance
lower
4 primary · 0 co-sponsors
Sponsors
Role
Legislator
Party
State
District
P
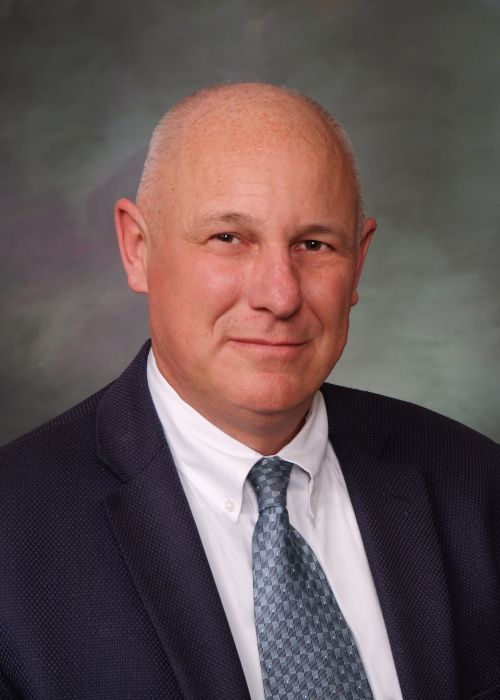
Bob Marshall
DDemocratic
P
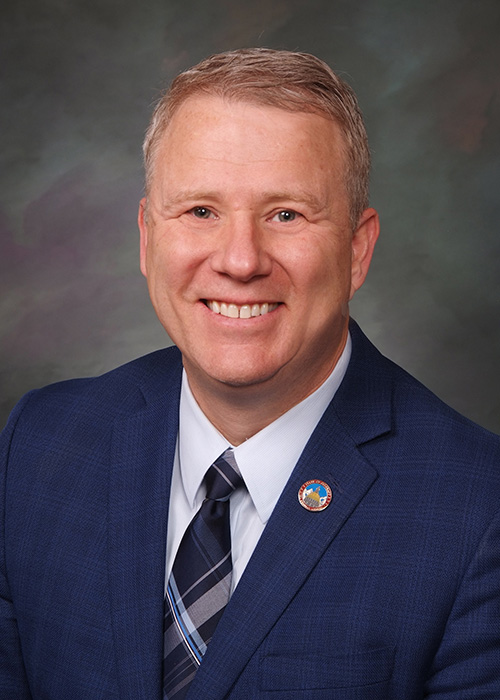
Chris Kolker
DDemocratic
P
JS
Jim Smallwood
RRepublican
P
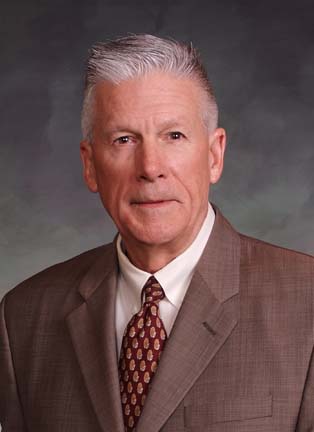
Rick Taggart
RRepublican
Ask Maddy
·
AI policy assistant
Ask Maddy about HB 23-1277
Scope: CO
Hi! I can help you understand HB 23-1277. What would you like to know?
Try one of these
i
Maddy answers using official bill text and legislative records. Always verify before sharing.
Sources cited inline